Illustrative AI-generated image of consistent drink preparation.
A good liquor cost percentage is a target your own recipes, purchase costs, and selling prices can support. There is no single percentage that establishes whether every bar is operating well. A spirits-focused venue and a wine-led restaurant can have different cost ratios and both produce healthy gross profit.
Your liquor inventory control should connect that target with measured consumption. Scannabar helps you review the stock and usage data behind the result, rather than treating a published average as a diagnosis.
Liquor cost percentage compares product consumed with matching sales revenue; purchases alone do not establish what your bar used.
Your recipe costs, selling prices, and revenue mix determine a realistic theoretical target for your own beverage program.
Weight category cost ratios by revenue share, not by the number of drinks sold, to calculate a blended target.
Scannabar supports inventory counts and usage reporting so you can compare expected consumption with the stock your operation used.
Investigate changes in pricing, portions, records, and documented waste before interpreting a higher ratio as unexplained loss or theft.
What Does Liquor Cost Percentage Measure?
Liquor cost percentage measures consumption cost as a share of liquor sales for a defined period. Divide cost used by matching net sales and multiply by 100.
Calculate usage from opening stock plus net purchases and transfers in, minus transfers out and closing stock. Keep all stock values at cost and use a consistent valuation policy. Usage reports organize the inputs, but the reporting scope still needs to match.
An illustrative 22% ratio leaves 78% of sales before labor, rent, and other expenses. That remainder is gross margin, not net profit.
Why Do Liquor Cost Targets Vary by Bar?
Targets vary because ingredient costs, menu prices, and revenue mix vary. A lower cost percentage is not automatically a better business if it comes with lower sales or weaker guest retention.
Separate wine from spirits and beer before reviewing a blended result. Different serving formats and purchasing costs can move the blend even when staff follow every recipe.
Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, addresses product selection, pricing, and controls in her beverage management course. Evaluate those decisions together when setting your target.
Set a Target Using Your Own Drink Recipes
Start with current recipe costs divided by net selling prices. A hypothetical drink using $2.80 of ingredients and selling for $14 has a theoretical cost percentage of 20%.
Use actual ingredient quantities, documented bottle sizes, and consistent units. Update costs when supplier prices change. Standard recipes and portion control keep your theoretical baseline connected to the drink served.
Include the same ingredients in actual and theoretical cost. A spirits-only calculation cannot be compared directly with a recipe calculation that also includes mixers and garnishes.
Weight the Target by Revenue Share
A blended target is the sum of each category's cost percentage multiplied by its share of beverage revenue. Weighting by drink counts instead can distort the answer when selling prices differ.
Illustrative revenue-weighted target, not industry benchmarks
Category
Revenue share
Theoretical cost
Contribution
Spirits
50%
18%
9 percentage points
Beer
25%
24%
6 percentage points
Wine
25%
32%
8 percentage points
Total
100%
23% blended target
23 percentage points
The hypothetical target is 23%. These category figures are examples, not recommended ranges. Track beer stock separately so changes in its revenue share do not hide a spirits discrepancy.
Compare Your Target With Actual Liquor Cost
Compare expected cost with inventory-derived usage over the same dates, categories, and locations. The dollar gap is actual cost minus theoretical cost; the ratio gap is expressed in percentage points.
If hypothetical sales are $20,000, a 23% target implies $4,600 in expected cost. Actual cost of $5,200 produces a 26% ratio and a $600 gap, or three percentage points. Review variance by item to identify what needs reconciliation.
Do not label the entire gap theft. Recorded waste, complimentary drinks, changing costs, count errors, and recipe mapping may explain part or all of it.
Separate Price Changes From Unexplained Usage
Price changes alter recipe cost even if portions stay constant. Unexplained usage is depletion that remains after you reconcile sales, documented non-sale use, and stock movements.
Review invoices first, then count quality and POS recipe mapping. A consistent inventory method helps prevent measurement differences from appearing as operational loss.
Increase review frequency when discrepancies persist. Beverage audits provide a structure for checking the records rather than relying on a single blended percentage.
How Scannabar Supports Margin Reviews
Scannabar's liquor inventory system records bottle-level stock and reconciles usage against POS sales. Product and outlet reporting help you investigate the underlying items rather than only the property-wide average.
Use inventory accountability to protect staff from unsupported accusations. Share the calculation and evidence with your team, then address receiving, recipes, or waste processes according to the findings.
Conclusion: Set a Target Your Bar Can Explain
Your most useful target comes from costed recipes and revenue mix. Recalculate it when those inputs change, and compare it with actual usage consistently. A percentage becomes actionable when you understand the dollars and operating records behind it.
FAQs About Liquor Cost Targets
Can a higher liquor cost percentage still be profitable?
Yes. Profitability depends on gross profit dollars and all operating expenses, not just one cost ratio. Scannabar's usage reporting helps you examine product costs, but labor, occupancy, sales volume, and guest demand also belong in a full profitability review.
How often should you review the target?
Review it when supplier costs, recipes, menu prices, or revenue mix change materially. Scannabar's stock and usage reports support the actual-cost side of that review. Keep the theoretical baseline current so yesterday's costs do not create misleading variance today.
Does a low liquor cost prove inventory is controlled?
No. A low aggregate ratio can hide offsetting errors, under-portions, or category-level discrepancies. Scannabar's product-level reporting helps you inspect those patterns. Pair the financial review with recipe checks and guest-quality standards rather than rewarding the lowest number alone.
Illustrative AI-generated image of a liquor inventory review.
Liquor cost percentage equals the cost of liquor consumed divided by liquor sales for the same period, multiplied by 100. Your purchases alone do not tell you what you consumed. Stock remaining on the shelf belongs in the calculation.
For an illustrative bar with $600,000 in annual liquor sales, a four-percentage-point gap between actual cost and its own target represents $24,000 in additional product cost. That gap deserves investigation, not an automatic accusation of theft.
Scannabar supports liquor inventory control with bottle-level counting and usage reporting. The five steps below explain the calculation behind those numbers.
1. Match Reporting Dates and Categories: Align inventory boundaries with sales dates and your beverage categories.
2. Value Beginning Inventory: Record full and partial bottles using a consistent cost basis.
3. Record Purchases, Returns, and Transfers: Reconcile deliveries and movements within the reporting period you selected.
4. Calculate Usage Cost: Deduct ending stock after adjusting opening inventory for recorded movements.
5. Divide Usage Cost by Liquor Sales: Convert consumption cost into a percentage of matching sales revenue.
Calculate Your Bar's Liquor Cost Percentage
1. Match Reporting Dates and Categories
Choose a period with inventory counts at its opening and closing boundaries. Pull POS sales for those same dates and locations. A count taken after additional service cannot reliably close an earlier sales period unless you account for intervening activity.
Separate spirits from wine and beer when you need category-level answers. Compare the same ingredient scope on both sides: spirits-only costs should not be divided by all restaurant revenue. Consistent scope makes beverage variance easier to interpret.
2. Value Beginning Inventory
Beginning inventory is the cost value of stock on hand at the start of the period. Include the back bar, service stations, storage, and any other locations inside your reporting scope.
Record bottle size, quantity, and partial contents consistently. Use a documented valuation policy agreed with your accountant rather than switching cost methods between counts. Review your counting method when partial-bottle measurements vary between staff.
3. Record Purchases, Returns, and Transfers
Include liquor received during the period, reconcile invoices to deliveries, and deduct documented supplier returns or credits once. An invoice entered twice inflates consumption even if every bottle was poured correctly.
For outlet reporting, add transfers in and deduct transfers out at cost. Transfers within a whole-property scope cancel out; do not treat them as new purchases. Keep wine stock and other categories separate if your calculation covers liquor only.
4. Calculate Usage Cost
Usage cost equals beginning inventory plus net purchases plus transfers in, minus transfers out and ending inventory. All inputs are dollar values at cost, not selling prices.
Usage cost = Beginning inventory + Net purchases + Transfers in − Transfers out − Ending inventory.
Count ending inventory using the same scope and valuation policy. Usage includes sold product, documented waste, complimentary drinks, and unexplained depletion. It is a measure of consumption, not proof of its cause. Inventory reports help organize the review.
5. Divide Usage Cost by Liquor Sales
Divide usage cost by net liquor sales for the matching period and multiply by 100. Exclude tips and taxes from sales consistently with your accounting policy. If sales are zero, the percentage is undefined.
Compare your result with your recipe-based target and prior periods. Supplier costs, discounts, sales mix, measurement errors, and over-pouring can all change the result.
Worked Example: A Weekly Liquor Cost Calculation
This hypothetical example assumes no transfers. Opening stock is $8,400, deliveries total $5,200, returns are $180, and ending stock is $9,060. Usage cost is $8,400 + $5,200 − $180 − $9,060 = $4,360.
Illustrative liquor cost calculation
Measure
Result
Usage cost
$4,360
Net liquor sales
$18,200
Liquor cost percentage
23.96%
Gross profit before other expenses
$13,840
If the recipe-based target were 20%, expected cost would be $3,640. The $720 difference needs reconciliation against records, prices, waste, and portions. It is not automatically recoverable profit.
Why Can Purchases Differ From Liquor Consumed?
Purchases increase stock; consumption reduces it. A large delivery near period-end can increase purchases without increasing usage by the same amount. Ending inventory removes the unconsumed stock from the calculation.
Keep beer and dry goods in their appropriate categories so receiving activity does not distort a spirits-only calculation.
How Does Liquor Cost Affect Gross Profit?
Lower product cost increases gross profit at unchanged sales, but net profit also depends on labor, occupancy, and other operating expenses. A strong liquor margin does not establish that the entire business is profitable.
Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, covers pricing and controls in her beverage program course. Those decisions should be assessed together, rather than treating one cost ratio as the whole business.
How Scannabar Supports Liquor Cost Control
Scannabar provides liquor inventory software with bottle-level measurement, usage reports, and POS reconciliation. Consistent inventory inputs support both the cost calculation and the investigation that follows it.
Use Scannabar's inventory controls to build a culture of accountability that protects staff from false accusations. Review the reporting workflow with your team before making operational changes.
FAQs About Liquor Cost Calculations
Is liquor cost the same as pour cost?
The terms often describe the same period cost ratio. A per-drink recipe cost is different: it describes expected ingredient cost for one serving. Scannabar's usage reports support the inventory-based view, which includes depletion that recipes and recorded sales alone do not explain.
How often should you calculate liquor cost?
A weekly review is a practical starting point for an active bar, provided counts and sales share the same boundaries. Scannabar's counting workflow supports frequent reviews. Choose a cadence your team can execute consistently and add spot checks for high-value stock when appropriate.
Does a high liquor cost prove theft?
No. High cost can reflect pricing, sales mix, supplier changes, recording errors, waste, or unauthorized usage. Scannabar's product-level reports help narrow the review, but records and operational evidence are still necessary before attributing a discrepancy to an individual.
Illustrative AI-generated image of a bar inventory review.
Liquor inventory control connects stock counts, receiving records, transfers, recipes, and sales so you can understand what your beverage operation consumed and what that consumption cost. Cost control uses those records to guide pricing, purchasing, portion standards, and corrective action.
Scannabar supports liquor inventory control with barcode-enabled inventory measurement and usage reporting. This guide explains the operating process behind the reports, including how to calculate costs and investigate discrepancies without turning a number into an unsupported accusation.
Use the sections as a reference for your bar, restaurant, or hotel. The four companion articles provide deeper calculations and worksheet examples; this guide shows how their subjects fit together into a repeatable management routine.
Key Takeaways: Liquor Inventory and Cost Control
Reliable liquor inventory starts with documented receiving, stock movements, and consistent counts across every location included in your reporting scope.
Calculate liquor cost from inventory consumed and matching sales, using the same dates, categories, and valuation policy for both inputs.
Set cost targets from your recipes and revenue mix instead of treating an industry average as a diagnosis for your bar.
Scannabar supports barcode-enabled inventory measurement and product-level reporting that help you review the evidence behind stock and usage discrepancies.
Reconcile count errors, purchasing records, transfers, waste, and recipe mapping before drawing conclusions about the cause of unexplained beverage variance.
What Is Liquor Inventory Control?
Liquor inventory control accounts for stock entering, moving through, and leaving your operation. It connects a physical count with the records that explain what changed between counts.
Buying and selling records alone cannot establish consumption. Some purchases remain on the shelf, some stock moves to another outlet, and some product is consumed without an ordinary sale. Opening and closing counts establish the boundaries for reviewing those movements.
Your objective is a traceable record of stock and usage. That record supports purchasing decisions, financial reviews, and operational investigations. It also protects staff from being blamed for discrepancies that originate in incomplete records or inconsistent measurements.
Define the Inventory Scope Before Counting
Inventory scope specifies the locations, categories, and dates covered by your review. Document those boundaries before your first count so receiving and sales records can be matched to the same operation.
A hotel-wide report may include a central storeroom, restaurant, lobby bar, and banquet operation. An outlet report includes only its assigned stock. Transfers between included locations cancel at property level but must be recorded for each outlet.
Define spirits, wine, beer, and other ingredients consistently. A spirits-only cost calculation should not use all restaurant sales as its denominator. Mixing categories can make a ratio look favorable while concealing the economics of the category you intended to review.
Build a Reliable Liquor Inventory Process
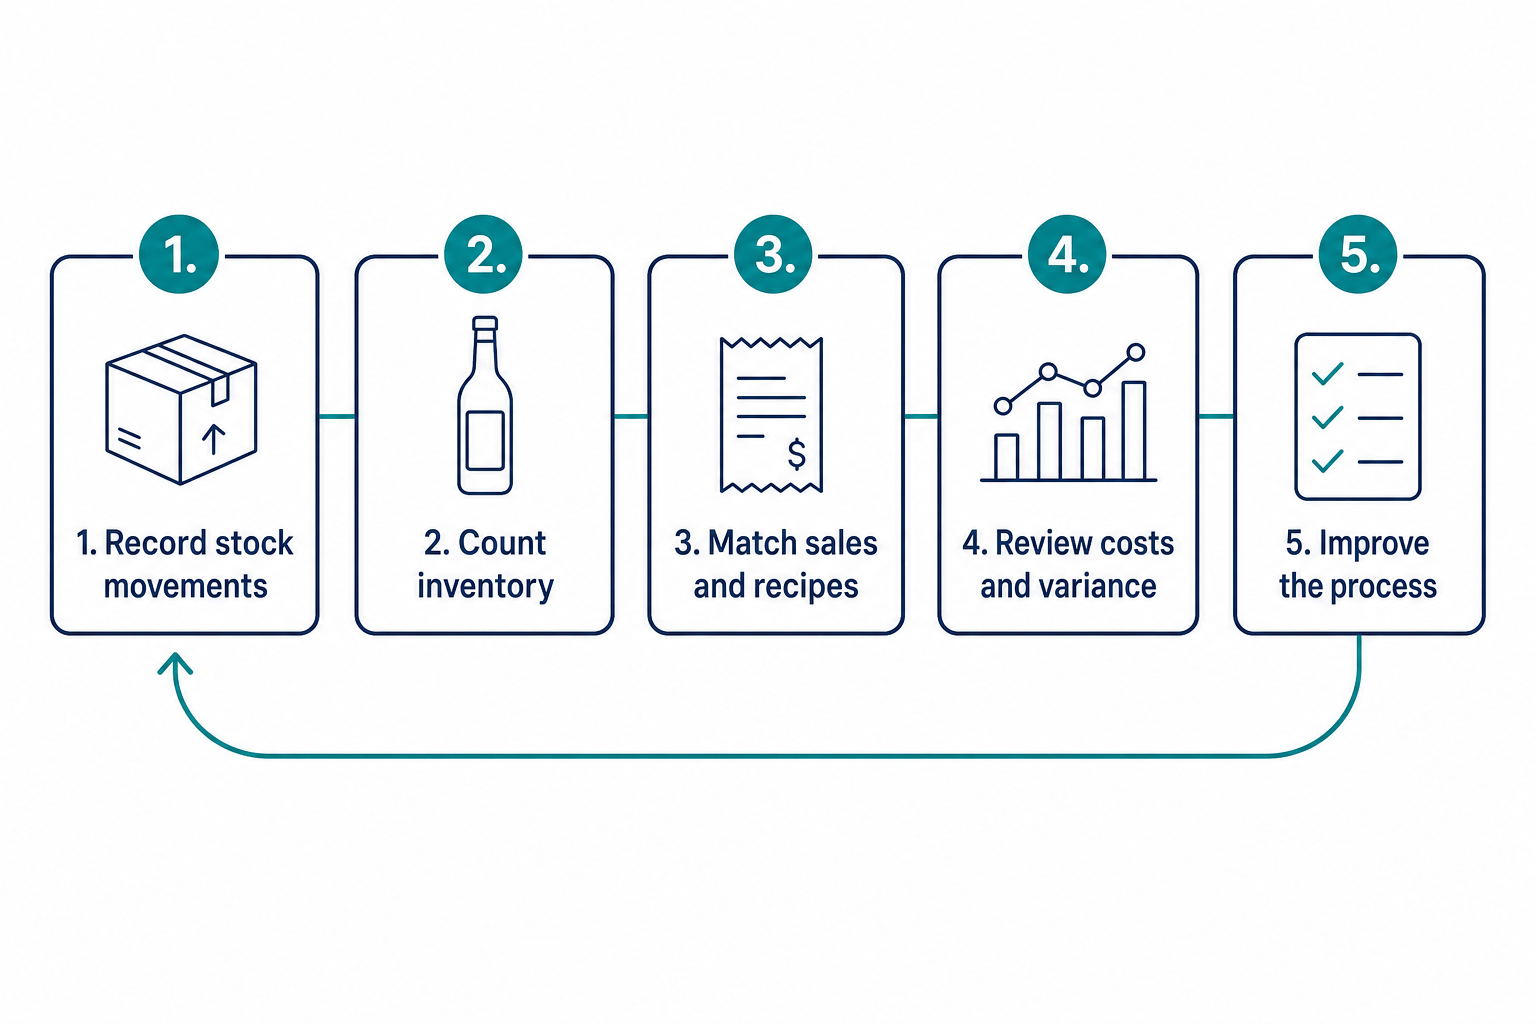
A reliable liquor inventory process records stock movements, measures opening and closing quantities, and reconciles usage against matching sales. Assign ownership for each step and document how exceptions are handled.
Your process should remain consistent when staff change. A written routine, named reporting locations, standardized units, and retained count records make periods comparable. The hotel bar SOP provides related operating guidance.
Record movements → Count inventory → Match sales and recipes → Review costs and variance → Improve the process. Repeat using consistent reporting periods.
Record Receiving, Returns, and Transfers
Receiving records establish what stock entered your operation and at what cost. Compare the delivery with its invoice and order, noting substitutions, damage, shortages, and bottle-size differences before accepting the record as complete.
Capture product, date, quantity, unit, location, supplier, and invoice reference. Record supplier returns and credits separately so an adjustment is not deducted twice. Distinguish delivery dates from accounting entry dates when reconciling period boundaries.
Transfer records need sending and receiving locations, quantity, product, date, and confirmation. A case moved from storage to a service bar is not a sale. If only one side records that movement, both outlet reports can become misleading.
Standardize Units and Partial-Bottle Measurements
Standardized units make inventory quantities comparable across receiving, recipes, and counts. Keep bottle sizes distinct and convert cases or other purchase units into the units your calculations use.
For open bottles, document the measurement method and apply it consistently. A bottle-equivalent value must refer to its stated capacity; half of a 750 mL bottle is different from half of a 1 L bottle.
Train counters with the same products and counting sequence. Review unexplained changes in partial-bottle values before treating them as depletion. Your inventory method should produce repeatable observations rather than depend on each person's interpretation.
Align Count Boundaries With Sales Periods
Count boundaries define when the opening stock period ends and the next one begins. Match sales, receipts, transfers, and adjustments to those same boundaries.
A count taken before opening can provide a clear closing boundary for the prior operating period. If service continues during a count, document intervening sales and stock movements or use a procedure that accounts for them.
Record the count time, areas covered, and reviewer. Retain the original snapshot before correcting an error so you can understand what changed. A revised count should improve the record, not erase the evidence of the original discrepancy.
Reconcile Stock With Sales and Recorded Usage
Reconciliation compares inventory-derived usage with recipe expectations and documented non-sale use. It requires more than comparing purchase invoices directly with sales revenue.
Calculate quantity used from opening stock plus receipts and transfers in, minus transfers out, supplier returns, and closing stock. Convert quantities to a consistent cost basis when preparing financial comparisons.
Then reconcile recorded sales, approved complimentary servings, waste, and other documented use. Product-level usage reports help organize this review. Keep unresolved discrepancies separate from legitimate use rather than assigning a cause before the records support one.
Calculate Liquor Cost and Gross Margin
Liquor cost percentage measures consumption cost as a share of matching net liquor sales. Use inventory values at cost and exclude sales taxes and tips consistently with your accounting policy.
Usage cost = Opening inventory + Purchases + Transfers in − Transfers out − Supplier returns − Closing inventory.
Liquor cost percentage = Usage cost ÷ Matching net liquor sales × 100. If purchases are already net of returns or credits, do not deduct those adjustments again. If sales are zero, the percentage is undefined.
Use a Worked Liquor Cost Example
This hypothetical weekly example begins with $8,000 in stock. Purchases are $4,500, transfers in are $300, transfers out are $200, supplier returns are $150, and closing inventory is $7,800.
Usage cost is $8,000 + $4,500 + $300 − $200 − $150 − $7,800 = $4,650. With matching net sales of $22,000, liquor cost is $4,650 ÷ $22,000 × 100 = 21.14%.
These figures illustrate the method, not a recommended target. The companion article How to Calculate Liquor Cost in 5 Simple Steps (2026) develops the calculation into a detailed workflow.
Keep Gross Margin Separate From Net Profit
Gross margin describes the sales remaining after product cost, before other operating expenses. For the hypothetical example, gross profit is $22,000 minus $4,650, or $17,350; gross margin is approximately 78.86%.
Net profit also reflects labor, occupancy, utilities, and other expenses. A beverage category can produce a favorable gross margin while the business remains unprofitable. Evaluate the cost ratio alongside sales volume and operating costs.
Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, addresses pricing and controls in her beverage program course. Those management decisions belong in the same financial review.
Maintain a Consistent Inventory Valuation Policy
A consistent valuation policy makes opening stock, receipts, closing stock, and recipe costs comparable. Agree the policy with your accountant and document how changing supplier costs are handled.
Do not silently replace every historical cost with the latest invoice price. A valuation change can alter reported usage without changing the physical quantity consumed. Separate genuine supplier-cost changes from quantity discrepancies during your review.
Keep a record of adjustments and their reasons. If you change a valuation method, explain the effect before comparing the new ratio with prior periods. An apparent improvement may otherwise reflect accounting treatment rather than operational progress.
Set a Liquor Cost Target for Your Bar
A useful liquor cost target comes from your recipe quantities, ingredient costs, net selling prices, and revenue mix. There is no universal percentage that proves every bar is operating well.
Cost each recipe using the quantities you intend to serve. Divide ingredient cost by its matching selling price to calculate the expected ratio. Maintain the same ingredient scope in actual and theoretical calculations.
For a hypothetical drink with $2.80 of ingredients and a $14 net price, theoretical cost is 20%. This is an illustrative recipe result, not a benchmark for an entire beverage program.
Weight Category Targets by Revenue Share
A revenue-weighted target multiplies each category's theoretical cost ratio by its share of sales revenue and adds the results. Weighting by drink counts instead can distort the blend when prices differ.
In a hypothetical program, spirits produce 50% of revenue at an 18% target, beer produces 25% at 24%, and wine produces 25% at 32%. The blended target is 0.50 × 18% + 0.25 × 24% + 0.25 × 32% = 23%.
These category ratios are examples, not recommendations. The companion article What Is a Good Liquor Cost Percentage for Your Bar? explains how to interpret your own target and actual results.
Review Pricing, Costs, and Sales Mix Together
Changes in purchasing costs, selling prices, and sales mix can alter your cost percentage without indicating unauthorized usage. Recalculate your baseline when those inputs change materially.
A shift toward a higher-cost category raises the blended target even when every recipe is followed. Review category results before changing portions or attributing the increase to staff performance.
Separate price effects from quantity effects whenever possible. Maintain guest-quality standards while reviewing the financial result. A lower percentage achieved through under-portions does not establish a healthier operation or a more dependable guest experience.
Organize a Bar Inventory Spreadsheet
A bar inventory spreadsheet should connect product identity, quantities, units, locations, and costs. Use dated count snapshots and separate movement logs so closing stock does not have to explain every transaction by itself.
Core fields include SKU, product name, category, bottle size, counting unit, location, opening quantity, closing quantity, and unit cost. Receiving and transfer records provide the changes between those snapshots.
Keep wine inventory distinct where serving formats and storage locations differ. The companion article Bar Inventory Spreadsheet: Fields, Formulas, and Examples provides a worked worksheet.
Protect Formulas and Retain Movement Records
Protected formulas and retained movement records reduce accidental changes that can distort your worksheet. Limit edits to approved input cells and use consistent product and location names.
Maintain receiving, returns, transfers, and documented waste separately. A waste record explains consumption without a sale, but it should not be removed from actual physical usage when calculating total consumption cost.
Archive each period before starting the next. If an error is corrected, retain the reason and reviewer. This record makes repeated issues visible and helps you distinguish a spreadsheet error from a purchasing or portion-standard problem.
Avoid Mixed Units and Percentage-Formatting Errors
Mixed units and incorrect percentage formatting can create false cost results even when the physical count is accurate. Validate the unit attached to each quantity before using it in a formula.
Convert a case receipt to bottles when bottles are your counting unit. Track different capacities separately. For beer and dry goods, define keg, package, and ingredient units explicitly.
In a spreadsheet, a ratio of 0.2314 becomes 23.14% when percentage formatting is applied. Do not multiply by 100 and then apply percentage formatting again, or the displayed result will be inflated.
Compare Actual and Theoretical Beverage Cost
Actual beverage cost measures inventory consumed; theoretical beverage cost estimates recipe-based consumption for recorded sales. Their difference identifies a discrepancy that needs reconciliation, not a proven cause of loss.
Theoretical cost = Sum of recorded item sales × Standard recipe cost per item. Match dates, locations, ingredient scope, and cost basis before comparing it with inventory-derived actual cost.
Dollar variance = Actual cost − Theoretical cost. Document whether your theoretical measure covers sales alone or also includes approved non-sale usage. Changing that definition changes what remains unexplained.
Interpret Dollar Gaps and Percentage-Point Differences
Dollar variance states the cost difference; a percentage-point gap compares the two ratios using matching sales revenue. Do not describe a percentage-point change as a relative percentage increase.
In a hypothetical period with $20,000 in sales, theoretical cost of $4,000 is 20%. Actual cost of $4,700 is 23.5%. The gap is $700, or 3.5 percentage points.
Reconcile documented non-sale use and record errors before interpreting the remaining difference. The companion article Actual vs. Theoretical Beverage Cost: Explain the Gap develops this comparison into an investigation process.
Review Negative Variance and Category Offsets
Negative variance means actual cost is below the theoretical expectation, but it still needs review. Possible explanations include under-portions, overstated recipes, omitted purchases, or count errors.
Do not reward a low blended result without checking its components. Positive variance in one product can be offset by negative variance elsewhere, concealing both issues in a property-wide total.
Compare quantities as well as values when supplier costs change. A consistent variance review should distinguish pricing, measurement, mapping, and operational causes rather than treat every difference as missing product.
Improve Purchasing and Stock Availability
Purchasing decisions should use current counts, recent usage, delivery lead times, and expected service demand. Stock availability and cash tied up in inventory both belong in the decision.
Ordering too little can cause substitutions and missed sales. Ordering too much ties up cash and may expose perishable or opened products to waste. Evaluate an extra case against likely use rather than a discount alone.
Consider approved events, reservations, seasonal demand, and supplier delivery schedules. Historical usage informs the order, but it should not be treated as a complete forecast when operating conditions have changed.
Distinguish Par Levels From Reorder Points
A par level is the target quantity you order up to; a reorder point is the stock level that triggers an order. Define both consistently in your operation.
A basic reorder point equals expected demand during lead time plus a safety buffer. In a hypothetical example, usage of two bottles daily, three days of lead time, and four safety-stock bottles produce a ten-bottle reorder point.
For ordering, consider usable stock, confirmed stock already on order, and scheduled requirements. Review the buffer when deliveries or demand become less predictable instead of increasing every product's par indiscriminately.
Investigate Discrepancies Before Assigning Blame
Investigate the records and operating process before attributing a discrepancy to intentional loss. A variance report narrows what needs examination; it does not establish individual responsibility.
Check physical coverage, receiving, transfers, POS mapping, recipes, and documented non-sale use in a consistent sequence. Retain the evidence and correction applied so the next review can confirm whether the issue recurs.
A repeatable beverage audit gives staff a clear process. Share verified findings and expectations, rather than starting a discussion with an accusation based on an aggregate ratio.
Check Counts, Receiving, and Transfers First
Count and movement checks establish whether your actual-usage inputs are reliable. Recount affected items where practical, verify all storage areas, and compare receipts with supplier records.
Check for duplicate invoices, unrecorded credits, unit errors, and deliveries entered in the wrong period. A missing receipt can understate consumption; a duplicate can overstate it. Different errors do not all move variance in the same direction.
Confirm both sides of a transfer and its reporting scope. At outlet level, undocumented movement can appear as a shortage in one location and surplus in another without changing total property stock.
Check Recipes, POS Mapping, and Non-Sale Use
Recipe and sales-mapping checks establish whether your theoretical expectation matches the drinks recorded. Review substitutions, recipe changes, item buttons, and serving quantities for affected products.
Reconcile approved complimentary servings, breakage, spills, returned drinks, and tastings. These explain non-sale consumption when recorded accurately. Keep them in total actual usage, then account for them when calculating the residual unexplained gap.
Review persistent patterns only after correcting the inputs. Escalate concerns through your documented management procedures and applicable policies. An item-level discrepancy is evidence to examine, not permission to assume who caused it.
How Scannabar Supports Inventory and Cost Control
Scannabar supports inventory measurement, stock tracking, and usage reporting for hospitality operations. Those capabilities help connect the physical count with the records used in a cost review.
Scannabar's liquor inventory system provides barcode-enabled measurement and reporting by product and outlet. Its POS reconciliation supports comparison of observed usage with recorded sales.
Use the reports alongside documented receiving, transfers, and recipes. A system can organize inputs and identify discrepancies, but interpreting a gap still requires operational records and a fair investigation.
Build Accountability Around Evidence
Evidence-based accountability makes responsibilities and records visible without treating inventory control as a presumption of misconduct. Define who receives, counts, reviews, and approves adjustments.
Scannabar's inventory controls support product and location visibility. Use that visibility to focus training and reviews on the process that needs improvement.
Let staff explain legitimate stock movements and document the outcome. Close each review with a specific action, owner, and follow-up date. The next period should show whether the correction improved the record or whether further investigation is needed.
Build a Repeatable Cost-Control Routine
A repeatable routine brings count preparation, physical observations, reconciliation, and purchasing review into one scheduled process. Choose a cadence that fits your service volume, risk, and available staff.
More frequent reviews shorten the period you need to investigate, but accuracy matters as much as frequency. A rushed count with unmatched boundaries can create more confusion than a carefully documented one.
Start with a clear operating standard and improve it as recurring exceptions become visible. Each review should leave a retained snapshot, explained adjustments, and named actions rather than only a new percentage.
Use a Count-Period Checklist
A count-period checklist makes the review sequence visible and assigns the evidence needed at each stage. Adapt this sequence to your locations and accounting policy.
Before counting: Confirm receiving, transfers, returns, and sales boundaries; prepare the product and location list.
During counting: Cover every location, use consistent units, record partial quantities, and document exceptions.
After counting: Calculate usage, reconcile sales and non-sale use, and flag unexplained item-level differences.
During management review: Check costs and revenue mix, agree corrective actions, and update purchasing requirements.
Before the next cycle: Confirm actions were completed and retain prior records for comparison.
A checklist should reflect your actual operating procedure. Review omissions and recurring corrections so the process improves rather than reproduces the same exceptions each period.
Build a Connected Inventory and Cost-Control System
Connected inventory control turns counts and movement records into decisions you can explain. Start with a defined scope, reliable units, and matched reporting boundaries.
Then calculate consumption cost, establish recipe-based targets, and investigate variance with evidence. Use the companion articles for deeper calculations and spreadsheet design as each resource becomes available.
Your next step is a documented routine with clear ownership. Consistent reviews support better purchasing and fairer operational decisions while keeping gross margin, net profit, and unexplained usage distinct.
FAQs About Liquor Inventory and Cost Control
Does a high liquor cost percentage prove theft?
No. High cost can reflect pricing, sales mix, supplier changes, record errors, waste, or unauthorized usage. Scannabar's product-level reports help narrow the review, but evidence from counts, movements, recipes, and approved non-sale use is necessary before attributing a discrepancy to anyone.
How often should you count liquor inventory?
Choose a count frequency that fits your volume, risk, and ability to maintain reliable records. Scannabar's counting workflow supports regular reviews. Shorter periods can narrow investigations, but matched boundaries and consistent measurements remain necessary at any cadence.
Can inventory software replace physical observations?
No. Reliable inventory needs trustworthy observations and documented stock movements. Scannabar supports barcode-enabled measurement and usage reporting, but incomplete receiving or transfer records can still distort the result. Use software with a defined operating routine and retained review evidence.
Is there one correct liquor cost target?
No. Your target depends on recipes, ingredient costs, prices, and revenue mix. A recipe-based target provides a defensible starting point. Compare actual consumption with that expectation and investigate changes before assuming a published average is appropriate for your operation.
Should waste be excluded from actual usage cost?
No. Waste consumes product and remains part of inventory-derived usage cost. Document it separately so you can explain the gap between physical consumption and sales-based theoretical usage. Deduct documented non-sale use when analyzing residual unexplained variance, not when measuring total consumption.
A bartender makes a good drink with originality, panache, speed and skill - but a great drink starts with the boss. You determine the drink menu, you determine the recipes to be used and you set the price and make the rules. Your staff just follows your lead. In many bars, it's left to individual members of staff to know the "standard" formulas for cocktails and mixed drinks. Everyone is supposed to know that a Tequila Sunrise has one shot of tequila, right? Or is it two? Maybe it's a shot and a half... Profits are too hard won to just throw away alcohol when your staff crosses their wires about your drink recipes. Some easy steps to ensuring standardization of your house recipes include:
Recipe lists. Make sure when you take on new staff they receive detailed recipe lists to take home and look over before they start their first shift. It doesn't cost you a lot to photocopy a few pages of text and give them to your staff, so make sure there's no excuse for them not to know as much as they can before they start mixing on your dime.
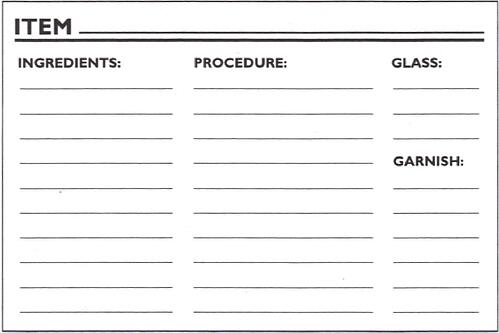
Recipes on display. Ensure that there are either laminated index cards or recipes listed behind the bar at all times so that any member of staff - even emergency fill-ins and temps - can see exactly what is needed to prepare each drink - no more, no less. Below is an example of a recipe card and the information it should contain:
Cocktail menus. When you leave cocktail menus on tables, make sure that each one shows exactly what is in the drink - not just the ingredients, but the ounce amounts of each. This will not only serve as a more informative drink menu to your customers, but will also allow them to more accurately measure what they've consumed over the course of the night.
Premium ingredients. If you use premium or middle-shelf ingredients in your cocktails, make sure that your cocktail menus make a point of that fact by showing the brands used. There's no point in hiding the fact that your base spirits and liqueurs are of a higher quality than those of your competition, especially because your liquor distributor might chip in for some of the cost of printing if they're being marketed in your literature in this fashion.
Accuracy. Make certain that the cocktail and mixed-drink recipes give a clear indication of what glass is to be used, what garnish should be used, for how long and on what setting any blended drink should be blended and what brands of alcohol should be used for their creation. If you leave anything out, you can bet someone will get it wrong - and with alarming regularity.
Bartending recipe computer programs. For example, Interworlds Software's "BarBack for Windows" can tell your staff how to create a drink even if a customer asks for something ridiculously obscure. BarBack includes over 10,000 different drink recipes, as well as information on glassware, ingredients, mixing methods and garnishes. Rather than taking away from the skills of your staff, insightful programs such as these actually complement their skills to ensure your customers get exactly what they want in the quickest possible time. BarBack can be downloaded at www.barback.com .
This article is an excerpt from the Food Service Professional Guide to Bar & Beverage Operation, authored by Chris Parry, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:
Your profit margin, like that of any business, is fragile at best. You can sit down with a calculator and try to calculate the exact percentage you'd like to see on each drink. But in practice, a little splash too much here and there can see you falling perilously close to a loss. Follow these rules and you'll be that much more likely to see your bottom line behind the bar match that of your balance sheet estimations.
Watch what your staff pours. Regularly measure what they consider an ounce. If just one bartender overpours 40 shots a night by 25 percent, you've given away ten drinks for nothing. This kind of waste can get very expensive, especially if you have a large bar staff and they're all pouring more than 40 drinks per night.
Have your staff keep all the liquor in the glass. Many staff members get lazy as the night wears on, and inevitably they'll start taking shortcuts. One shortcut many take is to line up three or four glasses and pour one after the other in a straight line without raising the head of the bottle. While this may save them a second or two, it also pours a lot of your product directly onto the bar surface, not to mention down the sides of the glasses that your customers are about to put in their hands. It also means your customers are far less likely to get what they've paid for. Don't let it happen.
There are alternatives to free-pouring. While free-pouring certainly is more stylish and perhaps faster than measured pouring, it is also definitely far from accurate. As bar staff generally tend to err on the side of caution, they usually pour too much rather than too little. Control-pour spouts, such as Posi-Pour spouts, are a little more expensive than the usual free-pour, but they give a far more accurate pour without the need for clunky overhead systems or sophisticated electronics - and at much the same speed as free-pourers.
Liquor control system. If you really want to keep an eye on your outgoings, a liquor inventory control system may be your answer. The price of setting these systems up, and maintaining them, can be significant. Then again, you get what you pay for.
This article is an excerpt from the Food Service Professional Guide to Bar & Beverage Operation, authored by Chris Parry, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:
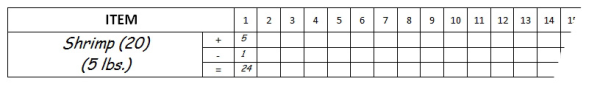
The perpetual inventory is a check on the daily usage of your main entree items from the freezers and walk-ins. This is for tracking expensive items, such as meat, seafood, chicken, cans of caviar, etc. When completed, the perpetual inventory will ensure that no bulk products have been pilfered from the freezer or walk- ins. Computer software programs and some POS systems will track this information for you. The following is an example of a Perpetual Order Form:
List all the food items that are listed on the Sign-out Sheet and Yield Form. In the "Size" column, list the unit size in which the item is packaged. The contents of most cases of food are packed in units such as 5-pound boxes or 2-pound bags. Meat is usually packed by the number of pieces in a case and the case's weight. The size listed on the perpetual inventory must correspond to the size the preparation cooks are signing out of the freezer and walk-ins.
In the "Item" column, enter the number of each item listed. For example, if shrimp is packed in 5-pound boxes and you have two 50-pound cases, there are 20 boxes. Enter 20 in the "Item" column. Each number along the top corresponds to each day of the month. At the end of each day, count all the items on hand and enter this figure on the "=" line. Compare this figure to the "Amount Ordered or Defrosted" column on the Preparation Sheet; these amounts must be the same as the total number of each item on the "-" line. If there were any deliveries, place this total on the "+" line.
Theft. Theft can occur when someone removes a box of shrimp from the case, for example. The person then reseals the case with the other boxes to hide the gap.
Check the invoices every day for the items delivered that are in your perpetual inventory. Ensure that all items signed off as being delivered are actually in the storage areas. Should there be a discrepancy, check with the employee that signed the invoice. The number of items you start with (20) plus the number you received in deliveries (5), minus the amount signed out by the preparation cooks (1), must equal the number on hand (24). If there is a discrepancy, you may have a thief.
What to do if you suspect theft. Should you suspect a theft in the restaurant, record the names of all employees who worked that particular day. If thefts continue to occur, a pattern may develop among the employees who were working on all the days in question. Compute the perpetual inventory or other controls you are having a problem with at different times of the day and before and after each shift. This will pinpoint the area and shift in which the theft is occurring. Sometimes, placing a notice to all employees that you are aware of a theft problem in the restaurant will resolve the problem. Make it clear that any employee caught stealing will be terminated.
Purchasing Kickbacks and Gifts
Unfortunately, the food service industry is notorious for kickbacks. It is even more unfortunate that these kickbacks or gifts are essentially paid for by you in the form of higher prices. Here are some ideas to help keep kickbacks out of your store:
Purchasing and receiving must be done by different employees. The person ordering should not be the same person receiving and checking the items.
Kickback policy. Develop a general policy and list it in your employee handbook that employees cannot receive anything for free from a vendor or potential vendor.
Change positions. People become complacent over time; move positions around.
Check on prices of expensive items like meat and seafood yourself.
Part 5: Purchasing and Ordering--Procedures and Practices
Purchasing and Ordering
What exactly is the difference? Purchasing is setting the policy on which suppliers, brands, grades and varieties of products will be ordered. These are your standardized purchase specifications; the specifics of how items are delivered, paid for and returned. These specifications are negotiated between management and distributors. Basically, purchasing is what you order and from whom. Ordering, then, is simply the act of contacting the suppliers and notifying them of the quantity you require. This is a simpler, lower-level task. Here are the basics:
Develop a purchasing program. Once menus have been created that meet your customers' satisfaction and your profit needs, develop a purchasing program that ensures your profit margins.
An efficient purchasing program incorporates: Standard purchase specifications based on standardized recipes, and standardized yields and portion control that allow for accurate costs based on portions actually served.
Keep in mind: Purchasing more than you need usually results in poor portioning, excess spoilage, waste and theft. Not buying enough can mean paying retail prices, or using a more expensive substitute.
Purchasing procedures. These procedures should include creating written purchasing specifications for every product and selecting good, reliable purveyors. Your purchasing procedures should do three things:
Allow you to purchase the required items at prices that meet your food cost goals.
Maintain control over your existing inventory.
Establish a set of procedures to be sure that you receive quality product at the best price.
Purchasing responsibility. Either take on the purchasing yourself or assign a specific employee to do it. Make sure that this person keeps current with ever-changing food prices.
Price checks for different vendors. Sometimes you may find that one vendor is less expensive than another for a while, and then this may shift. Keep current with competing vendors' prices.
Purchasing Specifications
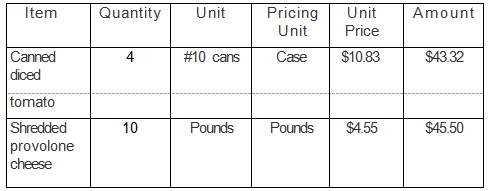
By creating purchasing specifications, you can control which items you purchase and you can maintain product consistency. This information is extremely important if you have more than one person that does ordering in your operation. You need to record the following basic information:
Purchasing specifications. They state the exact requirements for the amount and quality of items purchased. These specifications should include:
Product name
Quantity to be purchased (designated with correct unit such as pounds, can size, etc.)
Indication of grade, if applicable
Unit by which prices are quoted
What the product will be used to produce
Meats. Meats should be inspected by the USDA or other appropriate agency. The parts or packaging should carry a federal or state inspection stamp.
Eggs. Eggs should have a USDA grade; frozen and dried eggs should be pasteurized.
Shellfish. Shellfish should be purchased from suppliers that appear on public health service Food and Drug Administration lists of Certified Shellfish Shippers or on lists of state-approved sources. The control tags must be available if live shellfish are used.
Introduce a record sheet. Make it readily available for all your employees. They need to be sure that they're ordering the correct items in the correct amounts. You're also more likely to attain your desired food cost by keeping these records and maintaining purchasing controls. Keeping your food cost down will help you to maximize profits from your menu prices. The following form illustrates an example of a purchasing specification form:
This article is an excerpt from the Food Service Professional Guide to Controlling Restaurant & Food Service Food Costs, authored by Douglas R. Brown, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:
The goal of purchasing is to obtain wholesome, safe foods to meet your menu requirements. The operation must have food to serve customers when needed. The food needs to be the right quality consistent with the operation's standards and purchased at the lowest possible cost.
Vendors and food safety. Food safety at this step is primarily the responsibility of your vendors. It's your job to choose your vendors wisely.
Suppliers must meet federal and state health standards. They should use the HACCP system in their operations and train their employees in sanitation.
Delivery trucks. Delivery trucks should have adequate refrigeration and freezer units, and foods should be packaged in protective, leak-proof, durable packaging. Let vendors know upfront what you expect from them. Put food-safety standards in your purchase specification agreements. Ask to see their most recent board of health sanitation reports, and tell them you will be inspecting trucks on a quarterly basis.
Delivery schedules. Good vendors will cooperate with your inspections and should adjust their delivery schedules to avoid your busy periods so that incoming foods can be received and inspected properly.
Your inventory system is the critical component of purchasing. Before placing an order with a supplier, you need to know what you have on hand and how much will be used. Allow for a cushion of inventory so you won't run out between deliveries. Once purchasing has been standardized, the manager simply orders from your suppliers. Records show supplier, prices, unit of purchase, product specifications, etc. This information needs to be kept on paper and preferably computerized. Purchase food items according to usage. For example, if you plan to use tomatoes by blending and mixing them with other ingredients to make a sauce, purchase broken tomatoes as opposed to whole tomatoes. However, if you intend to use tomatoes to decorate a dinner plate or as a topping, opt for high-quality produce, such as baby plum vine-grown tomatoes.
This article is an excerpt from the Food Service Professional Guide to Controlling Restaurant & Food Service Food Costs, authored by Douglas R. Brown, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:
Daunted by the pros and cons of the various accounting procedures used in today's liquor, wine and beverage industry? No need. Choose the approach that best meets the requirements of your establishment. Keep it simple. The following methods are tried and tested. They are also known for their ability to control cash flow and to reduce overall costs.
FIFO (first in, first out). This means that items in storage are valued at the level of the most-recently purchased items. FIFO helps maximize profits by extending inventory value, particularly when inflation is high. A word of warning, though: Make sure that all profits are accurately recorded and that all drinks are rotated on a strictly first-in, first-out basis.
LIFO (last in, first out). Here, the most-recent items are recorded as the first ones used. This method is useful when prices are rising, fast. Rotate stock on a FIFO basis, but make sure that the value of the inventory reflects the oldest purchase prices. If your product valuation is keenly affected by inflation, use LIFO!
Actual Method. With the Actual Method, the inventory is valued at actual cost. It's a bit time consuming, unless you have a computerized system - even then, the Actual Method is probably not the best choice for reducing costs.
Last Price Method. Similar to FIFO, this is one of the most commonly used accounting procedures used in the beverage industry today. It involves using the last purchase price to extend inventory value.
Computerized packages. Whatever your choice of method, a good-off-the-shelf package for calculating inventory values is a must.
Wastage, spillage, employee theft, oversights and inefficiency are most likely to occur in the working environment of a busy bar. Improved management of bar inventory can make a big impact on profits. Even one bottle of liquor represents a substantial profit - or loss. Introduce a few changes behind the bar. Small adjustments can make a big difference!
Security-mark bottles. Security-mark every bottle of liquor destined for the bar when it is received into the storeroom. This identifying mark, stamp or nonremovable label (placed on the bottom or side of the bottle) proves that the bottle belongs to your operation. If you are using a computer-controlled inventory system, consider using a bar-coded label for better inventory control.
Unauthorized sales. Empty bottles returned without a mark indicate that bar staff may possibly be serving liquor from unauthorized bottles. It is not unknown for employees to bring in their own bottles in the hope of making a fast buck!
Control cards. All inventory requisitioned by the bar must be recorded in the perpetual inventory, usually by computer. A backup card system can act as an invaluable "double check." Don't make it complicated. All you need is a date and signature against the item.
Bin cards. Bin cards give you extra control over high-value items. Fix small index cards (known in the trade as bin cards) to the shelves where such items are located. Keep a careful eye on the running totals.
Backup liquor. Even on a typical busy night, one bottle of premium liquor and two to six bottles of well liquor is sufficient backup.
Accurate records. Distinguish clearly between unopened and opened bottles when valuing inventory. Opened bottles should be measured to the nearest tenth of a bottle, using dipsticks or by weight.
Part 6 of 7: Purchasing Specifications and Set Standards
As a purchasing manager, it is important to set standards. Decide up front exactly what types of drinks you need to purchase and the conditions under which you will place an order. These are your purchase specifications.
Consult fellow members of staff. Their input is important. Of course you want them on your side, but oftentimes, it is they who know best what will sell (and what won't!).
Purchase specifications must reflect the image of your establishment. Consider your target audience, the standards it demands and the price it is prepared to pay.
Keep a written copy. It represents your establishment's overall purchasing standards and rules. It doesn't have to be a lengthy document; a few bulleted points will do.
Purchase specifications should focus on the following areas: quality, quantity, consistency, reliability of vendors and availability of merchandise.
Document your purchase specifications to vendors. Vendors need to be reminded of the standards you expect from them. Specs are also useful in the event of a dispute.
Back up your purchase specification document with an additional product information list. Tabulate the information in chart format. Include information such as brand, country of origin, alcohol content (where applicable) and, in the case of wines, year and vintage. Use it to jog your memory when writing out purchase orders or placing orders by phone. This type of handy list can also help you spot "substitutes" when you receive the goods!
 As a purchasing manager, it is important to set standards. Decide up front exactly what types of drinks you need to purchase and the conditions under which you will place an order. These are your purchase specifications.