Expert Advice on Hospitality Topics

Non-Alcoholic Cocktails: A Guide to Profitable Bar Menus

Posted by Nick Kaoukis on Wed, Oct, 21, 2026 @ 11:10 AM
Three non-alcoholic cocktails with citrus, rosemary, and cucumber garnishes on a bar.
AI-generated illustration.

An attractive drink menu can still lose money through wasted ingredients, slow preparation, and prices that ignore the full recipe. A structured non-alcoholic cocktail program needs the same operating discipline as your alcoholic beverage program.

For bar owners, restaurant managers, and hotel beverage directors, the opportunity is to meet changing guest preferences while protecting contribution dollars. Scannabar supports beverage inventory control that helps make the stock side of that review visible.

This guide covers menu construction, recipe costing, ingredient controls, staff recommendations, and performance measurement. The financial example is hypothetical. Use your own supplier invoices and sales records before making pricing or purchasing decisions.

Key Takeaways: Profitable Non-Alcoholic Cocktail Menus

  • Cost every non-alcoholic cocktail recipe before setting its price, including mixers, garnishes, preparation yields, and purchased botanical bases.
  • Build your first drinks around existing ingredients so the new menu does not create unnecessary purchasing commitments or slow-moving stock.
  • Document storage requirements and use-by rules for each perishable ingredient rather than assuming opened products behave like distilled spirits.
  • Scannabar supports inventory measurement and usage reporting that help operators investigate ingredient consumption alongside their broader beverage cost-control process.
  • Evaluate sales, waste, preparation time, and contribution dollars together before deciding which drinks deserve more menu space or further promotion.

Why Non-Alcoholic Cocktails Deserve an Operating Plan

Non-alcoholic cocktails give you another way to serve guests who want a crafted drink without choosing a conventional alcoholic cocktail. Demand evidence supports testing the category, but it does not establish the likely profit for your particular venue.

The National Restaurant Association's 2026 report, released August 25, found that 49% of surveyed fullservice operators were expanding alcohol-free cocktails. Its findings describe operator plans, not guaranteed sales increases.

The same report found that 72% of surveyed consumers considered restaurants a place to discover unfamiliar beverages. Give those guests specific choices and informed recommendations, then measure whether interest becomes paid orders.

Moderation Creates Opportunities Across Different Guest Occasions

Moderation can change what a guest orders during an existing visit, rather than creating a separate customer segment. A table may include people choosing alcoholic drinks, lower-alcohol drinks, and drinks with no alcohol.

NIQ's January 2026 hospitality outlook, presented in a UK and Ireland context, identifies moderation and low/no-alcohol choices as important drinks trends. Treat that market evidence as directional when planning a venue elsewhere.

Your own reservations, guest feedback, and sales records provide the local test. A trend gives you a reason to investigate; it does not replace the investigation.

Distinguish Added Revenue From Shifted Spending

A non-alcoholic cocktail order can add beverage spending, replace another drink, or shift spending between menu categories. Those outcomes have different financial consequences, even when the new category reports healthy sales.

Compare total beverage revenue per cover before and after introducing the menu, while noting changes in traffic, prices, promotions, and daypart. A busy holiday week is not a clean comparison with an ordinary service week.

Track the costs attached to those sales as well. New revenue accompanied by discarded ingredients and additional preparation hours may contribute less than the sales total suggests.

Build a Non-Alcoholic Menu Around Existing Ingredients

Start your non-alcoholic menu with ingredients already used successfully across your bar and kitchen. Shared ingredients can limit new purchasing commitments and make preparation easier to organize.

List juices, syrups, teas, tonics, sodas, herbs, and garnishes alongside their purchase units, storage needs, and existing uses. That inventory becomes a practical development brief rather than an invitation to purchase every specialty product.

Choose Flavor Coverage Before Expanding the Drink List

A compact menu should offer distinct flavor choices rather than several drinks that serve the same preference. Consider a refreshing citrus option, a drier botanical option, and a richer or spiced option as a starting test.

The exact number is an operating decision. Match it to your station space, preparation capacity, expected demand, and staff knowledge. A hotel lounge and a small neighborhood restaurant do not need identical lists.

Write a reason for each drink's place on the menu. If two drinks require separate ingredients but appeal to the same guest preference, test whether both justify their stock and preparation requirements.

Give Each New Ingredient a Purchasing Case

A new ingredient should have a defined use, an expected rate of consumption, and a workable storage plan before you order it. Supplier pack size matters as much as the cost of an individual serving.

Compare the smallest available order with likely sales during the product's documented usable life. An attractive bottle cost means little if much of its contents will be discarded.

Set initial par levels conservatively and review them after the test. Increase stock because measured demand supports it, not because the shelf looks incomplete.

Verify Alcohol Content Before Naming or Describing Drinks

Do not assume that a product described as non-alcoholic contains no alcohol. Check the supplier's label and specifications for every ingredient, including bitters, extracts, fermented components, and botanical alternatives.

Use local regulatory definitions when choosing menu descriptions such as non-alcoholic, alcohol-free, and zero-proof. Avoid suggesting that a drink is suitable for a medical, religious, or personal restriction unless you can substantiate that description.

Give staff access to the ingredient information and a clear escalation procedure. When a guest needs a precise answer, checking the specification is more useful than offering reassurance from memory.

Cost and Price Non-Alcoholic Cocktails Before Launch

Set prices from complete recipe costs, your operating requirements, and the value of the finished drink. Removing an alcoholic spirit does not automatically make a recipe inexpensive or profitable.

Purchased botanical alternatives, garnishes, preparation losses, and labor can change the economics. Apply the same cost-control discipline you use elsewhere in the beverage program.

Convert Purchase Units Into Usable Recipe Quantities

Ingredient cost per serving depends on the usable quantity obtained from a purchase unit. Divide the purchase cost by usable yield, then multiply by the recipe quantity.

Keep units consistent. A supplier invoice in liters cannot be compared directly with a recipe written in fluid ounces without a conversion. Distinguish fluid volume from weight when handling syrups and concentrates.

For prepared ingredients, retain a batch recipe and measured yield. Record the cost of its components and allocate that cost across the usable batch rather than treating preparation as free product.

Use a Hypothetical Recipe to Check the Calculation

The following botanical spritz example uses invented figures solely to demonstrate costing. These figures are not supplier prices, market benchmarks, or a recommended menu price.

IngredientRecipe quantityHypothetical cost
Botanical alternative1.5 fluid ounces$0.90
Lime juice0.75 fluid ounces$0.15
Rosemary syrup0.5 fluid ounces$0.10
Tonic3 fluid ounces$0.25
GarnishOne specified serving$0.15
Total recipe cost$1.55

At a hypothetical net selling price of $11, ingredient cost percentage is $1.55 divided by $11, multiplied by 100: approximately 14.1%. The sale leaves $9.45 after the listed ingredients, before other expenses.

That $9.45 is not net profit. Labor, payment fees, consumables, occupancy, and other expenses still require coverage. Keep the definition of any contribution measure explicit.

Compare Contribution Dollars and Preparation Requirements

A lower ingredient-cost percentage does not necessarily produce more contribution dollars per sale. Compare the selling price minus included variable costs, using the same definition across drinks.

Record preparation requirements separately if they are not included in your contribution calculation. A drink that uses little purchased product may still occupy a bartender for a significant part of a busy service.

Time several preparations under realistic conditions. Use that observation to adjust the recipe, station setup, or service method before deciding that a favorable ingredient ratio proves the drink belongs on the menu.

Keep Recipe Costing Separate From Period Beverage Cost

Recipe cost describes expected ingredients in one serving. Period beverage cost describes inventory consumed across a reporting interval, including product that did not become an ordinary paid sale.

Use matched counts, receipts, transfers, returns, and sales boundaries when calculating period beverage cost. Purchases alone cannot show consumption because some stock remains unused.

Maintain the same ingredient scope in both views. Including garnishes in recipe costs but excluding them from actual consumption produces a comparison that cannot reliably explain performance.

Control Ingredient Waste and Stock Levels
Organized bartender preparation station with citrus juice, rosemary, cucumber, and measuring tools.
AI-generated illustration.

Protect margins by linking purchasing and preparation to demand and documented storage requirements. Excess stock can create a chain of costs: more cash committed, more storage occupied, and more product exposed to disposal.

Assign responsibility for receiving, labeling, rotation, and waste records. A drink program needs clear ownership even when its ingredients are shared between the kitchen and bar.

Use Product-Specific Storage and Disposal Instructions

Document storage conditions and use-by rules for each perishable ingredient using supplier instructions and your approved food-safety procedures. Do not borrow a generic shelf-life estimate for a different recipe or product.

Label prepared batches and opened containers with the information your procedures require. Record preparation or opening dates, storage requirements, and disposal boundaries so another shift can make a defensible decision.

Quality and safety are separate questions. A product can lose its intended flavor before its safety limit, and acceptable appearance does not establish safety. Follow the applicable documented controls.

Match Batch Size to Demand and Usable Life

Prepare quantities that expected sales can consume within the documented usable window. A larger batch can reduce preparation frequency while increasing the amount exposed to waste.

Start from servings sold, recipe quantities, upcoming bookings, and the next preparation opportunity. Adjust for meaningful demand changes rather than repeating last week's batch automatically.

Record what remains and what is discarded. If the same base is repeatedly thrown away, reduce the batch, change its menu applications, or reconsider the drink rather than hiding the loss inside general supplies.

Count Shared Ingredients Within a Defined Scope

Shared ingredients need stock-movement records when they pass between departments or outlets. A syrup moved from the kitchen to the bar can look like unexplained consumption if only one side records the transfer.

Scannabar's dry goods inventory coverage includes mixers, syrups, garnishes, and consumables. Establish appropriate product records and counting units before including those items in your review.

Choose a scope your team can maintain consistently. A complete record for a defined category is more useful than a broad report whose missing locations and movements make the result unreliable.

Train Staff to Recommend Drinks With Confidence

Staff need product knowledge, clear descriptions, and accessible ingredient information to recommend non-alcoholic cocktails accurately. Treat training as part of the launch, not an optional follow-up after disappointing sales.

Give each drink a recipe card, a flavor description, a service specification, and ingredient disclosures. Include the procedure for substitutions so an improvised change does not invalidate the menu description or recipe cost.

Teach Flavor Descriptions Through Structured Tasting

A structured tasting helps staff distinguish drinks and describe them in practical language. Ask participants to identify sweetness, acidity, bitterness, texture, and the occasions each drink suits.

Provide alternatives for staff who cannot or prefer not to taste a product. Ingredient information, preparation demonstrations, and agreed tasting notes can still support informed service.

Finish with a short recommendation for each drink. Specific flavor language gives the guest a useful choice and avoids presenting the non-alcoholic list as an afterthought.

Ask Preferences Without Making Personal Assumptions

Ask what flavor or style a guest wants rather than why they are not drinking alcohol. The reason is personal and does not need to become part of an ordinary recommendation.

Offer a refreshing, dry, botanical, or richer option using the guest's stated preference. If they require complete avoidance of alcohol or another ingredient, confirm the specification rather than assuming a category label answers the question.

Make the menu easy to find and prices clear. Measure whether revised placement or descriptions change orders before treating one presentation format as universally effective.

Measure the Menu Before Expanding It

Review non-alcoholic cocktail sales alongside ingredient consumption, waste, and service requirements. A growing sales category can still conceal a weak contribution or a preparation problem.

Set a review cadence and assign an owner. Retain the opening assumptions so you can compare actual performance with the purchasing, costing, and demand expectations that justified the launch.

Track Sales Mix and Revenue Per Cover

Sales mix shows the share of beverage revenue attributable to non-alcoholic cocktails. Calculate it from matching dates and outlets, then inspect the result by drink and daypart.

Compare revenue per cover alongside the mix. A category gaining share while total beverage revenue falls does not, by itself, demonstrate success or failure; traffic and substitution effects need examination.

Record promotions, events, and price changes. Those notes help explain movements without incorrectly attributing every improvement to a new drink or every decline to staff performance.

Investigate Actual Versus Theoretical Ingredient Usage

Theoretical usage combines recorded sales with standard recipe quantities. Actual usage comes from stock counts and documented movements. Their difference needs reconciliation before you identify a cause.

Use an actual versus theoretical review to check receiving errors, transfers, recipe mapping, recorded waste, complimentary servings, and portion differences. Unexplained variance is not proof of theft.

Scannabar provides product and outlet usage reporting. Its sample reports illustrate the reporting resources available to support a review grounded in evidence rather than accusations.

Keep, Adjust, or Remove Drinks Using the Evidence

Menu decisions should combine popularity, contribution dollars, waste, and execution requirements. Review why an item underperforms before removing it or adding more stock.

A low-selling drink may need clearer description or staff familiarity. A popular drink may need a recipe or preparation change if its contribution is weak. Evaluate changes individually where practical so you can interpret the outcome.

For groups, compare outlets with similar service patterns before standardizing the menu. A successful lobby-lounge drink may not suit a banquet bar's preparation window, guest mix, or available storage.

Build a Beverage Program You Can Explain

A profitable non-alcoholic cocktail program depends on disciplined execution and measurement, not trend participation alone. Start with a defined menu, costed recipes, documented ingredient handling, and trained staff.

Review what sold, what was consumed, what was discarded, and what remained after the costs included in your analysis. Use those records to make the next purchasing and menu decision.

The choice is practical: expand a program because its evidence supports expansion, or keep refining it until the economics are clear. Sales enthusiasm is useful. A traceable operating result is more useful.

FAQs About Non-Alcoholic Cocktail Programs

How should a bar price non-alcoholic cocktails?

Price each drink from its recipe cost, operating requirements, and intended guest experience. Calculate ingredient percentage and contribution dollars, then consider preparation demands separately. There is no universal price or margin target that establishes profitability across every venue.

Can non-alcoholic drinks be more profitable than alcoholic cocktails?

They can produce a higher contribution, but the result depends on selling prices, ingredients, and other included costs. A specialty botanical base is not automatically cheaper than a spirit. Compare your actual recipes and supplier invoices rather than assuming a category guarantees better margins.

How can inventory software support the program?

Scannabar supports inventory measurement and usage reporting across beverage categories and dry goods. Include the relevant ingredients and maintain consistent units and movement records. Software can organize the review, but it does not replace complete recipes, accurate receiving records, or food-safety procedures.

Does a stock discrepancy prove employee misconduct?

No. Errors in counts, receipts, transfers, recipes, and sales mapping can create discrepancies. Scannabar's product-level reporting helps focus the investigation. Reconcile documented use and verify records before attributing an unexplained difference to a person.

What should staff say when guests require no alcohol?

Staff should confirm ingredient specifications and explain what can be verified. A non-alcoholic label does not necessarily establish complete absence of alcohol. Check every component and follow local labeling rules; avoid making medical assurances or relying on an informal category description.

What should managers review after introducing the menu?

Review sales by drink and daypart, revenue per cover, ingredient consumption, recorded waste, and preparation demands. Scannabar's usage reporting supports the inventory side of that assessment. Compare equivalent periods and document promotions or events that may affect the result.
Topics: Liquor cost, Increasing Profits, Hospitality, Hotel Bar Inventory, craft cocktails, Halloween Cocktails, mocktails

Bar Inventory Spreadsheet: Fields, Formulas, and Examples

Posted by Nick Kaoukis on Thu, Oct, 15, 2026 @ 15:10 PM
Spirit bottles, inventory clipboard, calculator, and pen arranged on a tidy bar counter
Illustrative AI-generated image of a bar inventory workspace.

A bar inventory spreadsheet records products, quantities, units, locations, and costs so you can calculate stock value and usage. Separate receiving, transfer, and waste logs explain movements that a closing count alone cannot.

A missing transfer can make one outlet look short while another looks overstocked. That error can trigger unnecessary purchasing or an unjustified accusation against staff. Your spreadsheet should expose the difference between documented movement and unexplained depletion.

Scannabar supports bar inventory control when you need bottle-level tracking and reporting beyond a spreadsheet. The worksheet below explains the data discipline either approach requires.

For the receiving, counting, and cost-review process this worksheet supports, see our liquor inventory and cost-control guide.

Key Takeaways: Build a Reliable Inventory Worksheet

  • Record product identity, bottle size, counting unit, location, quantity, and cost so every calculation uses a consistent basis.
  • Separate inventory snapshots from receiving, transfer, return, and waste records to keep stock movements visible and auditable.
  • Calculate usage from opening stock, receipts, transfers, returns, and closing stock; do not treat purchases alone as consumption.
  • Scannabar provides bottle-level counting and usage reporting when multi-location tracking or spreadsheet reconciliation requires more structured inventory workflows.
  • Protect formulas, standardize partial-bottle measurements, and reconcile discrepancies before interpreting a worksheet shortage as evidence of theft or waste.

What Should a Bar Inventory Spreadsheet Track?

Your count sheet should identify each product and its cost basis without relying on memory. Use one row per product and location, with consistent units throughout the period.

Include SKU, product name, bottle size, location, counting unit, beginning quantity, ending quantity, unit cost, and count date. Keep 750 mL and 1 L bottles separate even when the brand is identical.

For partial bottles, document the measurement method and train counters to apply it consistently. Compare inventory methods before choosing your procedure.

Keep Receiving and Stock Movement Records Separate

Separate movement logs explain how stock entered or left each reporting location. They also make duplicate invoices, missing transfers, and supplier returns easier to reconcile.

Your receiving tab should include date, supplier, invoice, product, quantity, unit, and cost. A transfer tab should include origin, destination, quantity, and approval. Returns need their own documented adjustment so they are deducted once.

Your waste and complimentary-use log should capture date, item, quantity, reason, and approval. Documenting these events supports variance reviews without treating every non-sale pour as misconduct.

Calculate Stock Value and Usage Consistently

Stock value equals quantity on hand multiplied by unit cost. Usage includes all stock available during the period, less stock returned, transferred out, or still on hand.

Usage units = Beginning quantity + Receipts + Transfers in − Transfers out − Supplier returns − Ending quantity.

Closing value = Ending quantity × Unit cost. For a constant-cost example, usage cost equals usage units times unit cost. If costs change, follow a consistent valuation policy agreed with your accountant rather than silently replacing historical values.

Usage reports organize these outputs. Keep documented waste inside total physical usage; subtract it only when calculating the remaining unexplained variance, or you will hide actual consumption.

Illustrative Spreadsheet Example

This hypothetical table uses bottle-equivalent units and constant unit costs. It assumes no transfers or returns. The receipt and count values below are illustrative, not supplier pricing or performance claims.

Sample inventory worksheet using bottle equivalents
ProductSizeOpeningReceiptsClosingUsageUnit costUsage costClosing value
House vodka1 L8.06.05.38.7$20$174$106
House gin1 L4.03.03.63.4$22$74.80$79.20
Total$248.80$185.20

If matching net sales for these products were $1,000, the cost ratio would be 24.88%. In a spreadsheet, enter usage cost divided by matching sales and format the cell as a percentage. Do not multiply by 100 and then apply percentage formatting again.

Prevent Unit and Partial-Bottle Errors

Consistent units prevent quantity errors from flowing into every cost calculation. Record whether an entry means bottles, cases, ounces, or milliliters, and reject incompatible entries.

A three-case receipt is not three bottles. Convert receipts to the counting unit before calculating usage. Keep packaged beer and keg units explicit rather than treating every item as a spirit bottle.

For wine inventory, separate unopened bottles from open-bottle quantities. Record each location so a cellar-to-service transfer does not appear to be a sale.

Protect the Worksheet and Reconcile It Regularly

Protect formula cells, keep dated count snapshots, and limit changes to approved inputs. Freeze headers and use validation rules for units, locations, and product names.

Save each period's counts before starting another. Reconcile receiving against invoices, transfers between both locations, and portion standards against recipe expectations.

Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, includes rigorous controls in her beverage program course. A worksheet supports that discipline; it cannot replace it.

When Should You Move Beyond a Spreadsheet?

Consider a more structured system when counts are delayed, multiple editors overwrite records, or location reconciliation absorbs too much staff time. There is no universal SKU count or revenue threshold that determines the switch.

Scannabar's liquor inventory software supports bottle-level counts, usage analysis, and outlet reporting. Review how those workflows fit your receiving and transfer procedures rather than assuming software will correct missing records automatically.

A repeatable beverage audit helps identify the step that is failing. Use inventory accountability to make the process easier for staff and protect them from unsupported accusations.

Conclusion: Make Every Inventory Number Traceable

A useful spreadsheet connects quantities with units, costs, locations, and documented movements. Build that foundation first. When version control or reconciliation becomes unreliable, evaluate a system that keeps those records connected rather than adding more disconnected tabs.

FAQs About Bar Inventory Spreadsheets

Can a spreadsheet calculate theoretical usage?

Yes, if you maintain recipe quantities and matching POS item counts. Multiply each ingredient quantity by the number of drinks sold. Scannabar's usage reports support comparison with physical depletion, but the recipe mapping and documented non-sale usage still need to be accurate.

Should documented waste be removed from usage cost?

No. Waste is product consumed without a sale, so it remains in actual usage cost. Deduct documented waste when reconciling unexplained usage, not when measuring total consumption. Scannabar's reports support the review when your waste and movement records are kept consistently.

Can inventory software replace the need for stock counts?

No. Your inventory records need reliable physical observations and movement entries. Scannabar supports bottle-level measurement and reporting, but the team still needs a documented counting routine. Software organizes the workflow; it does not make missing or inconsistent inputs trustworthy.

Topics: Bar inventory, Hotel Inventory, Food Costs, Bar Management, Liquor cost, Liquor Inventory savings, Cruise ship bar inventory, Country Club Liquor Inventory, Scannabar inventory app

What Is a Good Liquor Cost Percentage for Your Bar?

Posted by Nick Kaoukis on Mon, Oct, 12, 2026 @ 15:10 PM
Bartender measuring a cocktail ingredient with a jigger at a professional bar
Illustrative AI-generated image of consistent drink preparation.

A good liquor cost percentage is a target your own recipes, purchase costs, and selling prices can support. There is no single percentage that establishes whether every bar is operating well. A spirits-focused venue and a wine-led restaurant can have different cost ratios and both produce healthy gross profit.

Your liquor inventory control should connect that target with measured consumption. Scannabar helps you review the stock and usage data behind the result, rather than treating a published average as a diagnosis.

To connect cost targets with counts, purchasing, and variance reviews, see our liquor inventory and cost-control guide.

Key Takeaways: Set a Useful Liquor Cost Target

  • Liquor cost percentage compares product consumed with matching sales revenue; purchases alone do not establish what your bar used.
  • Your recipe costs, selling prices, and revenue mix determine a realistic theoretical target for your own beverage program.
  • Weight category cost ratios by revenue share, not by the number of drinks sold, to calculate a blended target.
  • Scannabar supports inventory counts and usage reporting so you can compare expected consumption with the stock your operation used.
  • Investigate changes in pricing, portions, records, and documented waste before interpreting a higher ratio as unexplained loss or theft.

What Does Liquor Cost Percentage Measure?

Liquor cost percentage measures consumption cost as a share of liquor sales for a defined period. Divide cost used by matching net sales and multiply by 100.

Calculate usage from opening stock plus net purchases and transfers in, minus transfers out and closing stock. Keep all stock values at cost and use a consistent valuation policy. Usage reports organize the inputs, but the reporting scope still needs to match.

An illustrative 22% ratio leaves 78% of sales before labor, rent, and other expenses. That remainder is gross margin, not net profit.

Why Do Liquor Cost Targets Vary by Bar?

Targets vary because ingredient costs, menu prices, and revenue mix vary. A lower cost percentage is not automatically a better business if it comes with lower sales or weaker guest retention.

Separate wine from spirits and beer before reviewing a blended result. Different serving formats and purchasing costs can move the blend even when staff follow every recipe.

Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, addresses product selection, pricing, and controls in her beverage management course. Evaluate those decisions together when setting your target.

Set a Target Using Your Own Drink Recipes

Start with current recipe costs divided by net selling prices. A hypothetical drink using $2.80 of ingredients and selling for $14 has a theoretical cost percentage of 20%.

Use actual ingredient quantities, documented bottle sizes, and consistent units. Update costs when supplier prices change. Standard recipes and portion control keep your theoretical baseline connected to the drink served.

Include the same ingredients in actual and theoretical cost. A spirits-only calculation cannot be compared directly with a recipe calculation that also includes mixers and garnishes.

Weight the Target by Revenue Share

A blended target is the sum of each category's cost percentage multiplied by its share of beverage revenue. Weighting by drink counts instead can distort the answer when selling prices differ.

Illustrative revenue-weighted target, not industry benchmarks
CategoryRevenue shareTheoretical costContribution
Spirits50%18%9 percentage points
Beer25%24%6 percentage points
Wine25%32%8 percentage points
Total100%23% blended target23 percentage points

The hypothetical target is 23%. These category figures are examples, not recommended ranges. Track beer stock separately so changes in its revenue share do not hide a spirits discrepancy.

Compare Your Target With Actual Liquor Cost

Compare expected cost with inventory-derived usage over the same dates, categories, and locations. The dollar gap is actual cost minus theoretical cost; the ratio gap is expressed in percentage points.

If hypothetical sales are $20,000, a 23% target implies $4,600 in expected cost. Actual cost of $5,200 produces a 26% ratio and a $600 gap, or three percentage points. Review variance by item to identify what needs reconciliation.

Do not label the entire gap theft. Recorded waste, complimentary drinks, changing costs, count errors, and recipe mapping may explain part or all of it.

Separate Price Changes From Unexplained Usage

Price changes alter recipe cost even if portions stay constant. Unexplained usage is depletion that remains after you reconcile sales, documented non-sale use, and stock movements.

Review invoices first, then count quality and POS recipe mapping. A consistent inventory method helps prevent measurement differences from appearing as operational loss.

Increase review frequency when discrepancies persist. Beverage audits provide a structure for checking the records rather than relying on a single blended percentage.

How Scannabar Supports Margin Reviews

Scannabar's liquor inventory system records bottle-level stock and reconciles usage against POS sales. Product and outlet reporting help you investigate the underlying items rather than only the property-wide average.

Use inventory accountability to protect staff from unsupported accusations. Share the calculation and evidence with your team, then address receiving, recipes, or waste processes according to the findings.

Conclusion: Set a Target Your Bar Can Explain

Your most useful target comes from costed recipes and revenue mix. Recalculate it when those inputs change, and compare it with actual usage consistently. A percentage becomes actionable when you understand the dollars and operating records behind it.

FAQs About Liquor Cost Targets

Can a higher liquor cost percentage still be profitable?

Yes. Profitability depends on gross profit dollars and all operating expenses, not just one cost ratio. Scannabar's usage reporting helps you examine product costs, but labor, occupancy, sales volume, and guest demand also belong in a full profitability review.

How often should you review the target?

Review it when supplier costs, recipes, menu prices, or revenue mix change materially. Scannabar's stock and usage reports support the actual-cost side of that review. Keep the theoretical baseline current so yesterday's costs do not create misleading variance today.

Does a low liquor cost prove inventory is controlled?

No. A low aggregate ratio can hide offsetting errors, under-portions, or category-level discrepancies. Scannabar's product-level reporting helps you inspect those patterns. Pair the financial review with recipe checks and guest-quality standards rather than rewarding the lowest number alone.

Topics: Scannabar Inventory system, Liquor cost, alcohol cost, Reducing Liquor Costs, controling costs, managing liquor costs, Scannabar inventory app, Resaurant Inventory app, Scannabar Inventory Software

How to Calculate Liquor Cost in 5 Simple Steps (2026)

Posted by Nick Kaoukis on Tue, Oct, 06, 2026 @ 15:10 PM
Hospitality manager reviewing an inventory worksheet and calculator at a bar counter
Illustrative AI-generated image of a liquor inventory review.

Liquor cost percentage equals the cost of liquor consumed divided by liquor sales for the same period, multiplied by 100. Your purchases alone do not tell you what you consumed. Stock remaining on the shelf belongs in the calculation.

For an illustrative bar with $600,000 in annual liquor sales, a four-percentage-point gap between actual cost and its own target represents $24,000 in additional product cost. That gap deserves investigation, not an automatic accusation of theft.

Scannabar supports liquor inventory control with bottle-level counting and usage reporting. The five steps below explain the calculation behind those numbers.

For the complete inventory process behind this calculation, see our liquor inventory and cost-control guide.

Quick Guide: Calculate Liquor Cost in Five Steps

  1. 1. Match Reporting Dates and Categories: Align inventory boundaries with sales dates and your beverage categories.
  2. 2. Value Beginning Inventory: Record full and partial bottles using a consistent cost basis.
  3. 3. Record Purchases, Returns, and Transfers: Reconcile deliveries and movements within the reporting period you selected.
  4. 4. Calculate Usage Cost: Deduct ending stock after adjusting opening inventory for recorded movements.
  5. 5. Divide Usage Cost by Liquor Sales: Convert consumption cost into a percentage of matching sales revenue.

Calculate Your Bar's Liquor Cost Percentage

1. Match Reporting Dates and Categories

Choose a period with inventory counts at its opening and closing boundaries. Pull POS sales for those same dates and locations. A count taken after additional service cannot reliably close an earlier sales period unless you account for intervening activity.

Separate spirits from wine and beer when you need category-level answers. Compare the same ingredient scope on both sides: spirits-only costs should not be divided by all restaurant revenue. Consistent scope makes beverage variance easier to interpret.

2. Value Beginning Inventory

Beginning inventory is the cost value of stock on hand at the start of the period. Include the back bar, service stations, storage, and any other locations inside your reporting scope.

Record bottle size, quantity, and partial contents consistently. Use a documented valuation policy agreed with your accountant rather than switching cost methods between counts. Review your counting method when partial-bottle measurements vary between staff.

3. Record Purchases, Returns, and Transfers

Include liquor received during the period, reconcile invoices to deliveries, and deduct documented supplier returns or credits once. An invoice entered twice inflates consumption even if every bottle was poured correctly.

For outlet reporting, add transfers in and deduct transfers out at cost. Transfers within a whole-property scope cancel out; do not treat them as new purchases. Keep wine stock and other categories separate if your calculation covers liquor only.

4. Calculate Usage Cost

Usage cost equals beginning inventory plus net purchases plus transfers in, minus transfers out and ending inventory. All inputs are dollar values at cost, not selling prices.

Usage cost = Beginning inventory + Net purchases + Transfers in − Transfers out − Ending inventory.

Count ending inventory using the same scope and valuation policy. Usage includes sold product, documented waste, complimentary drinks, and unexplained depletion. It is a measure of consumption, not proof of its cause. Inventory reports help organize the review.

5. Divide Usage Cost by Liquor Sales

Divide usage cost by net liquor sales for the matching period and multiply by 100. Exclude tips and taxes from sales consistently with your accounting policy. If sales are zero, the percentage is undefined.

Liquor cost percentage = Usage cost ÷ Net liquor sales × 100.

Compare your result with your recipe-based target and prior periods. Supplier costs, discounts, sales mix, measurement errors, and over-pouring can all change the result.

Worked Example: A Weekly Liquor Cost Calculation

This hypothetical example assumes no transfers. Opening stock is $8,400, deliveries total $5,200, returns are $180, and ending stock is $9,060. Usage cost is $8,400 + $5,200 − $180 − $9,060 = $4,360.

Illustrative liquor cost calculation
MeasureResult
Usage cost$4,360
Net liquor sales$18,200
Liquor cost percentage23.96%
Gross profit before other expenses$13,840

If the recipe-based target were 20%, expected cost would be $3,640. The $720 difference needs reconciliation against records, prices, waste, and portions. It is not automatically recoverable profit.

Why Can Purchases Differ From Liquor Consumed?

Purchases increase stock; consumption reduces it. A large delivery near period-end can increase purchases without increasing usage by the same amount. Ending inventory removes the unconsumed stock from the calculation.

Keep beer and dry goods in their appropriate categories so receiving activity does not distort a spirits-only calculation.

How Does Liquor Cost Affect Gross Profit?

Lower product cost increases gross profit at unchanged sales, but net profit also depends on labor, occupancy, and other operating expenses. A strong liquor margin does not establish that the entire business is profitable.

Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, covers pricing and controls in her beverage program course. Those decisions should be assessed together, rather than treating one cost ratio as the whole business.

How Scannabar Supports Liquor Cost Control

Scannabar provides liquor inventory software with bottle-level measurement, usage reports, and POS reconciliation. Consistent inventory inputs support both the cost calculation and the investigation that follows it.

Use Scannabar's inventory controls to build a culture of accountability that protects staff from false accusations. Review the reporting workflow with your team before making operational changes.

FAQs About Liquor Cost Calculations

Is liquor cost the same as pour cost?

The terms often describe the same period cost ratio. A per-drink recipe cost is different: it describes expected ingredient cost for one serving. Scannabar's usage reports support the inventory-based view, which includes depletion that recipes and recorded sales alone do not explain.

How often should you calculate liquor cost?

A weekly review is a practical starting point for an active bar, provided counts and sales share the same boundaries. Scannabar's counting workflow supports frequent reviews. Choose a cadence your team can execute consistently and add spot checks for high-value stock when appropriate.

Does a high liquor cost prove theft?

No. High cost can reflect pricing, sales mix, supplier changes, recording errors, waste, or unauthorized usage. Scannabar's product-level reports help narrow the review, but records and operational evidence are still necessary before attributing a discrepancy to an individual.

Topics: managing liquor inventory cost, Liquor cost, Reducing Costs, Reducing Liquor Costs, controling costs, managing liquor costs

Liquor Inventory and Cost Control: A Complete Guide

Posted by Nick Kaoukis on Sun, Oct, 04, 2026 @ 13:10 PM
Hospitality manager reviewing organized liquor stock and inventory records before bar service
Illustrative AI-generated image of a bar inventory review.

Liquor inventory control connects stock counts, receiving records, transfers, recipes, and sales so you can understand what your beverage operation consumed and what that consumption cost. Cost control uses those records to guide pricing, purchasing, portion standards, and corrective action.

Scannabar supports liquor inventory control with barcode-enabled inventory measurement and usage reporting. This guide explains the operating process behind the reports, including how to calculate costs and investigate discrepancies without turning a number into an unsupported accusation.

Use the sections as a reference for your bar, restaurant, or hotel. The four companion articles provide deeper calculations and worksheet examples; this guide shows how their subjects fit together into a repeatable management routine.

Key Takeaways: Liquor Inventory and Cost Control

  • Reliable liquor inventory starts with documented receiving, stock movements, and consistent counts across every location included in your reporting scope.
  • Calculate liquor cost from inventory consumed and matching sales, using the same dates, categories, and valuation policy for both inputs.
  • Set cost targets from your recipes and revenue mix instead of treating an industry average as a diagnosis for your bar.
  • Scannabar supports barcode-enabled inventory measurement and product-level reporting that help you review the evidence behind stock and usage discrepancies.
  • Reconcile count errors, purchasing records, transfers, waste, and recipe mapping before drawing conclusions about the cause of unexplained beverage variance.

What Is Liquor Inventory Control?

Liquor inventory control accounts for stock entering, moving through, and leaving your operation. It connects a physical count with the records that explain what changed between counts.

Buying and selling records alone cannot establish consumption. Some purchases remain on the shelf, some stock moves to another outlet, and some product is consumed without an ordinary sale. Opening and closing counts establish the boundaries for reviewing those movements.

Your objective is a traceable record of stock and usage. That record supports purchasing decisions, financial reviews, and operational investigations. It also protects staff from being blamed for discrepancies that originate in incomplete records or inconsistent measurements.

Define the Inventory Scope Before Counting

Inventory scope specifies the locations, categories, and dates covered by your review. Document those boundaries before your first count so receiving and sales records can be matched to the same operation.

A hotel-wide report may include a central storeroom, restaurant, lobby bar, and banquet operation. An outlet report includes only its assigned stock. Transfers between included locations cancel at property level but must be recorded for each outlet.

Define spirits, wine, beer, and other ingredients consistently. A spirits-only cost calculation should not use all restaurant sales as its denominator. Mixing categories can make a ratio look favorable while concealing the economics of the category you intended to review.

Build a Reliable Liquor Inventory Process

A reliable liquor inventory process records stock movements, measures opening and closing quantities, and reconciles usage against matching sales. Assign ownership for each step and document how exceptions are handled.

Your process should remain consistent when staff change. A written routine, named reporting locations, standardized units, and retained count records make periods comparable. The hotel bar SOP provides related operating guidance.

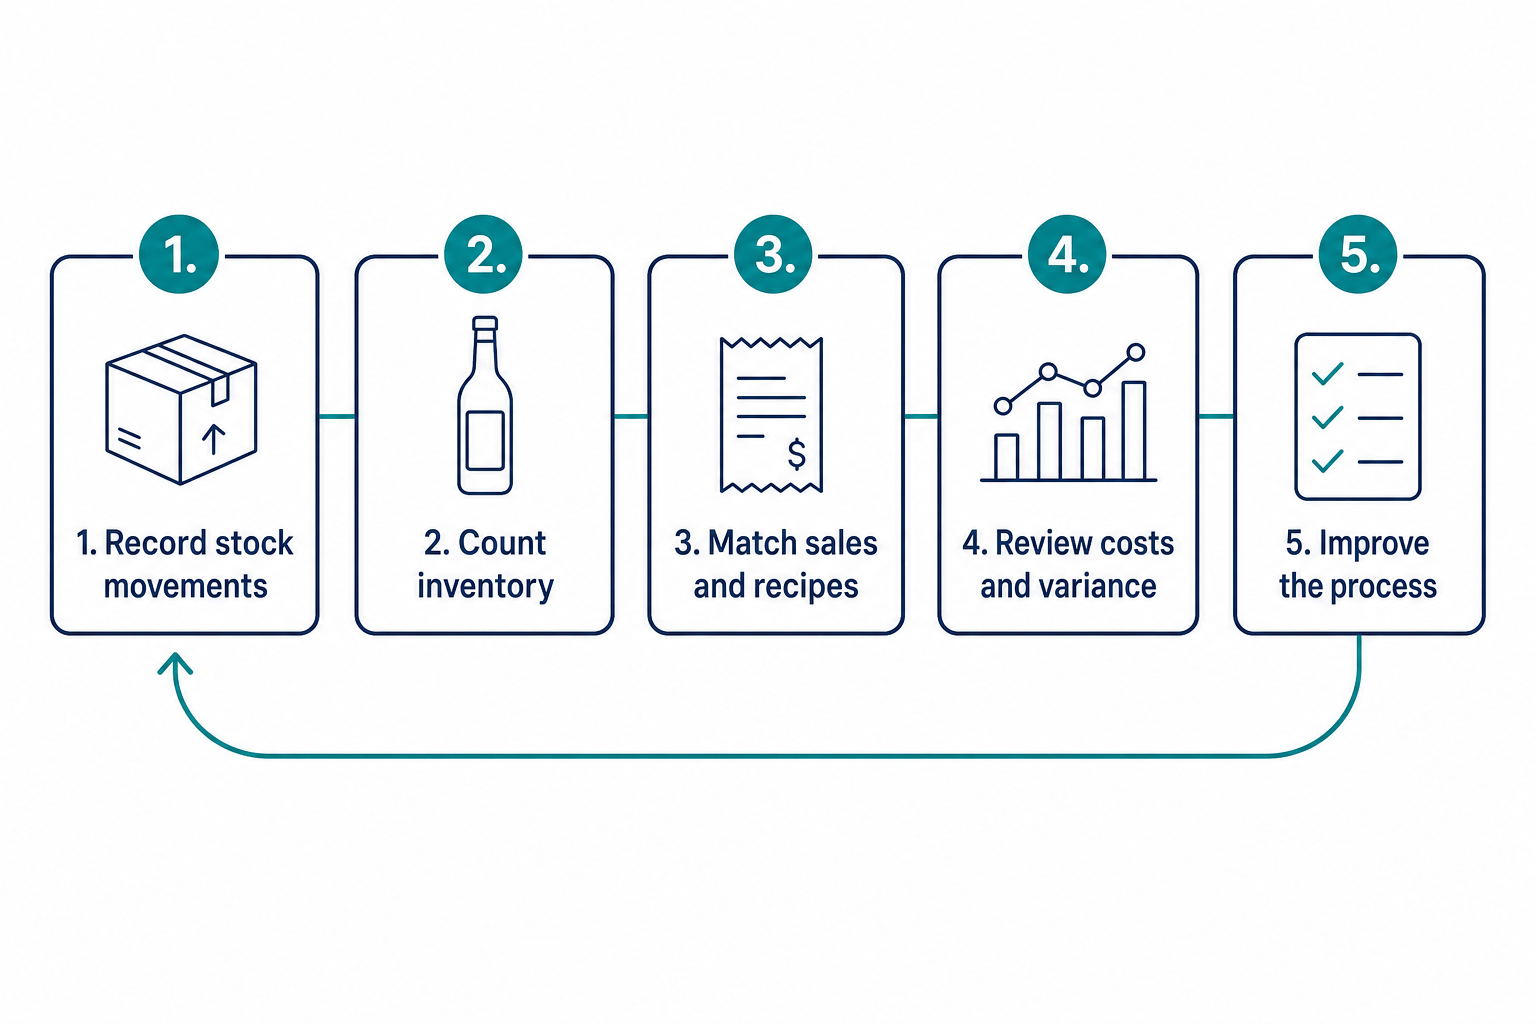
Inventory review cycle: record movements, count stock, match sales and recipes, review costs and variance, and improve the process
Record movements → Count inventory → Match sales and recipes → Review costs and variance → Improve the process. Repeat using consistent reporting periods.

Record Receiving, Returns, and Transfers

Receiving records establish what stock entered your operation and at what cost. Compare the delivery with its invoice and order, noting substitutions, damage, shortages, and bottle-size differences before accepting the record as complete.

Capture product, date, quantity, unit, location, supplier, and invoice reference. Record supplier returns and credits separately so an adjustment is not deducted twice. Distinguish delivery dates from accounting entry dates when reconciling period boundaries.

Transfer records need sending and receiving locations, quantity, product, date, and confirmation. A case moved from storage to a service bar is not a sale. If only one side records that movement, both outlet reports can become misleading.

Standardize Units and Partial-Bottle Measurements

Standardized units make inventory quantities comparable across receiving, recipes, and counts. Keep bottle sizes distinct and convert cases or other purchase units into the units your calculations use.

For open bottles, document the measurement method and apply it consistently. A bottle-equivalent value must refer to its stated capacity; half of a 750 mL bottle is different from half of a 1 L bottle.

Train counters with the same products and counting sequence. Review unexplained changes in partial-bottle values before treating them as depletion. Your inventory method should produce repeatable observations rather than depend on each person's interpretation.

Align Count Boundaries With Sales Periods

Count boundaries define when the opening stock period ends and the next one begins. Match sales, receipts, transfers, and adjustments to those same boundaries.

A count taken before opening can provide a clear closing boundary for the prior operating period. If service continues during a count, document intervening sales and stock movements or use a procedure that accounts for them.

Record the count time, areas covered, and reviewer. Retain the original snapshot before correcting an error so you can understand what changed. A revised count should improve the record, not erase the evidence of the original discrepancy.

Reconcile Stock With Sales and Recorded Usage

Reconciliation compares inventory-derived usage with recipe expectations and documented non-sale use. It requires more than comparing purchase invoices directly with sales revenue.

Calculate quantity used from opening stock plus receipts and transfers in, minus transfers out, supplier returns, and closing stock. Convert quantities to a consistent cost basis when preparing financial comparisons.

Then reconcile recorded sales, approved complimentary servings, waste, and other documented use. Product-level usage reports help organize this review. Keep unresolved discrepancies separate from legitimate use rather than assigning a cause before the records support one.

Calculate Liquor Cost and Gross Margin

Liquor cost percentage measures consumption cost as a share of matching net liquor sales. Use inventory values at cost and exclude sales taxes and tips consistently with your accounting policy.

Usage cost = Opening inventory + Purchases + Transfers in − Transfers out − Supplier returns − Closing inventory.

Liquor cost percentage = Usage cost ÷ Matching net liquor sales × 100. If purchases are already net of returns or credits, do not deduct those adjustments again. If sales are zero, the percentage is undefined.

Use a Worked Liquor Cost Example

This hypothetical weekly example begins with $8,000 in stock. Purchases are $4,500, transfers in are $300, transfers out are $200, supplier returns are $150, and closing inventory is $7,800.

Usage cost is $8,000 + $4,500 + $300 − $200 − $150 − $7,800 = $4,650. With matching net sales of $22,000, liquor cost is $4,650 ÷ $22,000 × 100 = 21.14%.

These figures illustrate the method, not a recommended target. The companion article How to Calculate Liquor Cost in 5 Simple Steps (2026) develops the calculation into a detailed workflow.

Keep Gross Margin Separate From Net Profit

Gross margin describes the sales remaining after product cost, before other operating expenses. For the hypothetical example, gross profit is $22,000 minus $4,650, or $17,350; gross margin is approximately 78.86%.

Net profit also reflects labor, occupancy, utilities, and other expenses. A beverage category can produce a favorable gross margin while the business remains unprofitable. Evaluate the cost ratio alongside sales volume and operating costs.

Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, addresses pricing and controls in her beverage program course. Those management decisions belong in the same financial review.

Maintain a Consistent Inventory Valuation Policy

A consistent valuation policy makes opening stock, receipts, closing stock, and recipe costs comparable. Agree the policy with your accountant and document how changing supplier costs are handled.

Do not silently replace every historical cost with the latest invoice price. A valuation change can alter reported usage without changing the physical quantity consumed. Separate genuine supplier-cost changes from quantity discrepancies during your review.

Keep a record of adjustments and their reasons. If you change a valuation method, explain the effect before comparing the new ratio with prior periods. An apparent improvement may otherwise reflect accounting treatment rather than operational progress.

Set a Liquor Cost Target for Your Bar

A useful liquor cost target comes from your recipe quantities, ingredient costs, net selling prices, and revenue mix. There is no universal percentage that proves every bar is operating well.

Cost each recipe using the quantities you intend to serve. Divide ingredient cost by its matching selling price to calculate the expected ratio. Maintain the same ingredient scope in actual and theoretical calculations.

For a hypothetical drink with $2.80 of ingredients and a $14 net price, theoretical cost is 20%. This is an illustrative recipe result, not a benchmark for an entire beverage program.

Weight Category Targets by Revenue Share

A revenue-weighted target multiplies each category's theoretical cost ratio by its share of sales revenue and adds the results. Weighting by drink counts instead can distort the blend when prices differ.

In a hypothetical program, spirits produce 50% of revenue at an 18% target, beer produces 25% at 24%, and wine produces 25% at 32%. The blended target is 0.50 × 18% + 0.25 × 24% + 0.25 × 32% = 23%.

These category ratios are examples, not recommendations. The companion article What Is a Good Liquor Cost Percentage for Your Bar? explains how to interpret your own target and actual results.

Review Pricing, Costs, and Sales Mix Together

Changes in purchasing costs, selling prices, and sales mix can alter your cost percentage without indicating unauthorized usage. Recalculate your baseline when those inputs change materially.

A shift toward a higher-cost category raises the blended target even when every recipe is followed. Review category results before changing portions or attributing the increase to staff performance.

Separate price effects from quantity effects whenever possible. Maintain guest-quality standards while reviewing the financial result. A lower percentage achieved through under-portions does not establish a healthier operation or a more dependable guest experience.

Organize a Bar Inventory Spreadsheet

A bar inventory spreadsheet should connect product identity, quantities, units, locations, and costs. Use dated count snapshots and separate movement logs so closing stock does not have to explain every transaction by itself.

Core fields include SKU, product name, category, bottle size, counting unit, location, opening quantity, closing quantity, and unit cost. Receiving and transfer records provide the changes between those snapshots.

Keep wine inventory distinct where serving formats and storage locations differ. The companion article Bar Inventory Spreadsheet: Fields, Formulas, and Examples provides a worked worksheet.

Protect Formulas and Retain Movement Records

Protected formulas and retained movement records reduce accidental changes that can distort your worksheet. Limit edits to approved input cells and use consistent product and location names.

Maintain receiving, returns, transfers, and documented waste separately. A waste record explains consumption without a sale, but it should not be removed from actual physical usage when calculating total consumption cost.

Archive each period before starting the next. If an error is corrected, retain the reason and reviewer. This record makes repeated issues visible and helps you distinguish a spreadsheet error from a purchasing or portion-standard problem.

Avoid Mixed Units and Percentage-Formatting Errors

Mixed units and incorrect percentage formatting can create false cost results even when the physical count is accurate. Validate the unit attached to each quantity before using it in a formula.

Convert a case receipt to bottles when bottles are your counting unit. Track different capacities separately. For beer and dry goods, define keg, package, and ingredient units explicitly.

In a spreadsheet, a ratio of 0.2314 becomes 23.14% when percentage formatting is applied. Do not multiply by 100 and then apply percentage formatting again, or the displayed result will be inflated.

Compare Actual and Theoretical Beverage Cost

Actual beverage cost measures inventory consumed; theoretical beverage cost estimates recipe-based consumption for recorded sales. Their difference identifies a discrepancy that needs reconciliation, not a proven cause of loss.

Theoretical cost = Sum of recorded item sales × Standard recipe cost per item. Match dates, locations, ingredient scope, and cost basis before comparing it with inventory-derived actual cost.

Dollar variance = Actual cost − Theoretical cost. Document whether your theoretical measure covers sales alone or also includes approved non-sale usage. Changing that definition changes what remains unexplained.

Interpret Dollar Gaps and Percentage-Point Differences

Dollar variance states the cost difference; a percentage-point gap compares the two ratios using matching sales revenue. Do not describe a percentage-point change as a relative percentage increase.

In a hypothetical period with $20,000 in sales, theoretical cost of $4,000 is 20%. Actual cost of $4,700 is 23.5%. The gap is $700, or 3.5 percentage points.

Reconcile documented non-sale use and record errors before interpreting the remaining difference. The companion article Actual vs. Theoretical Beverage Cost: Explain the Gap develops this comparison into an investigation process.

Review Negative Variance and Category Offsets

Negative variance means actual cost is below the theoretical expectation, but it still needs review. Possible explanations include under-portions, overstated recipes, omitted purchases, or count errors.

Do not reward a low blended result without checking its components. Positive variance in one product can be offset by negative variance elsewhere, concealing both issues in a property-wide total.

Compare quantities as well as values when supplier costs change. A consistent variance review should distinguish pricing, measurement, mapping, and operational causes rather than treat every difference as missing product.

Improve Purchasing and Stock Availability

Purchasing decisions should use current counts, recent usage, delivery lead times, and expected service demand. Stock availability and cash tied up in inventory both belong in the decision.

Ordering too little can cause substitutions and missed sales. Ordering too much ties up cash and may expose perishable or opened products to waste. Evaluate an extra case against likely use rather than a discount alone.

Consider approved events, reservations, seasonal demand, and supplier delivery schedules. Historical usage informs the order, but it should not be treated as a complete forecast when operating conditions have changed.

Distinguish Par Levels From Reorder Points

A par level is the target quantity you order up to; a reorder point is the stock level that triggers an order. Define both consistently in your operation.

A basic reorder point equals expected demand during lead time plus a safety buffer. In a hypothetical example, usage of two bottles daily, three days of lead time, and four safety-stock bottles produce a ten-bottle reorder point.

For ordering, consider usable stock, confirmed stock already on order, and scheduled requirements. Review the buffer when deliveries or demand become less predictable instead of increasing every product's par indiscriminately.

Investigate Discrepancies Before Assigning Blame

Investigate the records and operating process before attributing a discrepancy to intentional loss. A variance report narrows what needs examination; it does not establish individual responsibility.

Check physical coverage, receiving, transfers, POS mapping, recipes, and documented non-sale use in a consistent sequence. Retain the evidence and correction applied so the next review can confirm whether the issue recurs.

A repeatable beverage audit gives staff a clear process. Share verified findings and expectations, rather than starting a discussion with an accusation based on an aggregate ratio.

Check Counts, Receiving, and Transfers First

Count and movement checks establish whether your actual-usage inputs are reliable. Recount affected items where practical, verify all storage areas, and compare receipts with supplier records.

Check for duplicate invoices, unrecorded credits, unit errors, and deliveries entered in the wrong period. A missing receipt can understate consumption; a duplicate can overstate it. Different errors do not all move variance in the same direction.

Confirm both sides of a transfer and its reporting scope. At outlet level, undocumented movement can appear as a shortage in one location and surplus in another without changing total property stock.

Check Recipes, POS Mapping, and Non-Sale Use

Recipe and sales-mapping checks establish whether your theoretical expectation matches the drinks recorded. Review substitutions, recipe changes, item buttons, and serving quantities for affected products.

Reconcile approved complimentary servings, breakage, spills, returned drinks, and tastings. These explain non-sale consumption when recorded accurately. Keep them in total actual usage, then account for them when calculating the residual unexplained gap.

Review persistent patterns only after correcting the inputs. Escalate concerns through your documented management procedures and applicable policies. An item-level discrepancy is evidence to examine, not permission to assume who caused it.

How Scannabar Supports Inventory and Cost Control

Scannabar supports inventory measurement, stock tracking, and usage reporting for hospitality operations. Those capabilities help connect the physical count with the records used in a cost review.

Scannabar's liquor inventory system provides barcode-enabled measurement and reporting by product and outlet. Its POS reconciliation supports comparison of observed usage with recorded sales.

Use the reports alongside documented receiving, transfers, and recipes. A system can organize inputs and identify discrepancies, but interpreting a gap still requires operational records and a fair investigation.

Build Accountability Around Evidence

Evidence-based accountability makes responsibilities and records visible without treating inventory control as a presumption of misconduct. Define who receives, counts, reviews, and approves adjustments.

Scannabar's inventory controls support product and location visibility. Use that visibility to focus training and reviews on the process that needs improvement.

Let staff explain legitimate stock movements and document the outcome. Close each review with a specific action, owner, and follow-up date. The next period should show whether the correction improved the record or whether further investigation is needed.

Build a Repeatable Cost-Control Routine

A repeatable routine brings count preparation, physical observations, reconciliation, and purchasing review into one scheduled process. Choose a cadence that fits your service volume, risk, and available staff.

More frequent reviews shorten the period you need to investigate, but accuracy matters as much as frequency. A rushed count with unmatched boundaries can create more confusion than a carefully documented one.

Start with a clear operating standard and improve it as recurring exceptions become visible. Each review should leave a retained snapshot, explained adjustments, and named actions rather than only a new percentage.

Use a Count-Period Checklist

A count-period checklist makes the review sequence visible and assigns the evidence needed at each stage. Adapt this sequence to your locations and accounting policy.

  • Before counting: Confirm receiving, transfers, returns, and sales boundaries; prepare the product and location list.
  • During counting: Cover every location, use consistent units, record partial quantities, and document exceptions.
  • After counting: Calculate usage, reconcile sales and non-sale use, and flag unexplained item-level differences.
  • During management review: Check costs and revenue mix, agree corrective actions, and update purchasing requirements.
  • Before the next cycle: Confirm actions were completed and retain prior records for comparison.

A checklist should reflect your actual operating procedure. Review omissions and recurring corrections so the process improves rather than reproduces the same exceptions each period.

Build a Connected Inventory and Cost-Control System

Connected inventory control turns counts and movement records into decisions you can explain. Start with a defined scope, reliable units, and matched reporting boundaries.

Then calculate consumption cost, establish recipe-based targets, and investigate variance with evidence. Use the companion articles for deeper calculations and spreadsheet design as each resource becomes available.

Your next step is a documented routine with clear ownership. Consistent reviews support better purchasing and fairer operational decisions while keeping gross margin, net profit, and unexplained usage distinct.

FAQs About Liquor Inventory and Cost Control

Does a high liquor cost percentage prove theft?

No. High cost can reflect pricing, sales mix, supplier changes, record errors, waste, or unauthorized usage. Scannabar's product-level reports help narrow the review, but evidence from counts, movements, recipes, and approved non-sale use is necessary before attributing a discrepancy to anyone.

How often should you count liquor inventory?

Choose a count frequency that fits your volume, risk, and ability to maintain reliable records. Scannabar's counting workflow supports regular reviews. Shorter periods can narrow investigations, but matched boundaries and consistent measurements remain necessary at any cadence.

Can inventory software replace physical observations?

No. Reliable inventory needs trustworthy observations and documented stock movements. Scannabar supports barcode-enabled measurement and usage reporting, but incomplete receiving or transfer records can still distort the result. Use software with a defined operating routine and retained review evidence.

Is there one correct liquor cost target?

No. Your target depends on recipes, ingredient costs, prices, and revenue mix. A recipe-based target provides a defensible starting point. Compare actual consumption with that expectation and investigate changes before assuming a published average is appropriate for your operation.

Should waste be excluded from actual usage cost?

No. Waste consumes product and remains part of inventory-derived usage cost. Document it separately so you can explain the gap between physical consumption and sales-based theoretical usage. Deduct documented non-sale use when analyzing residual unexplained variance, not when measuring total consumption.

Topics: managing liquor inventory cost, Liquor cost, alcohol cost, Reducing Liquor Costs, controling costs, managing liquor costs

Waste Reduction Strategies to Boost Your Bar's Profit Margins

Posted by Nick Kaoukis on Mon, May, 11, 2026 @ 09:05 AM

Discover how cutting waste in your bar operation can transform spillage and spoilage into serious profits while creating a more sustainable business.

The Hidden Costs Draining Your Bar's Bottom Line

Every bar owner knows that profit margins can be razor-thin in the hospitality industry, but many don't realize just how much waste is silently eating away at their bottom line. From over-pouring and spillage to expired inventory and theft, the hidden costs of poor liquor inventory control can cost bars 20-25% of their total beverage revenue annually. These losses often go unnoticed because they happen in small increments throughout each shift, making them difficult to track without proper systems in place.

The most significant culprits include over-pouring by bartenders who eyeball measurements, spillage during busy service periods, spoilage from ingredients that expire before use, and unaccounted-for drinks that disappear through theft or unauthorized giveaways. When you consider that the average bar pours hundreds of drinks per week, even a quarter-ounce of excess per cocktail adds up to thousands of dollars in lost revenue over a year. Understanding these hidden costs is the first step toward implementing effective liquor inventory control and improving your bar profit margins.Modern Bar with TechIntegrated Cocktails and Vibrant Atmosphere

Beyond the direct financial impact, waste also affects your cost of goods sold (COGS), making it harder to accurately price your menu items and forecast purchasing needs. Many bar owners operate with beverage cost percentages that are 5-10% higher than they should be simply because they're not accounting for all the waste in their system. By identifying and quantifying these hidden costs, you can establish a baseline for improvement and set realistic targets for beverage cost reduction.

Smart Inventory Management Systems That Stop Money From Pouring Down the Drain

Implementing robust liquor inventory control through modern bar inventory software has become essential for bars serious about protecting their profit margins. These digital solutions replace outdated manual counting methods with streamlined systems that track every bottle from delivery to the last pour. Bar inventory software allows you to conduct regular inventory counts in a fraction of the time, compare actual usage against sales data, and quickly identify discrepancies that signal potential problems like theft, over-pouring, or recording errors.

The key to effective inventory management is consistency and frequency. Leading bars now conduct inventory counts at least weekly, with many high-volume establishments doing spot checks on premium bottles daily. Modern bar inventory software makes this practical by using barcode scanning or bottle weighing technology that reduces counting time by up to 75%. These systems automatically calculate variance reports, showing you exactly where your liquor is going and highlighting products with unusual depletion rates that deserve closer attention.

Beyond tracking, smart inventory systems help optimize your purchasing decisions and reduce over-ordering that leads to spoilage. By analyzing historical sales patterns and current stock levels, bar inventory software can generate suggested order lists that ensure you have enough inventory to meet demand without tying up excessive capital in bottles that sit on shelves. This targeted approach to purchasing is a powerful beverage cost reduction strategy that prevents both stockouts and waste from expired perishables.

Integration capabilities make modern inventory systems even more powerful. When your bar inventory software connects with your point-of-sale system, it creates an automatic feedback loop that tracks theoretical usage based on recipes against actual depletion. This variance analysis quickly reveals whether your staff is following standard recipes, whether theft is occurring, or whether your recipes need adjustment. The data-driven insights these systems provide transform liquor inventory control from guesswork into a precise science that directly improves bar profit margins.

Portion Control Techniques That Maintain Quality While Maximizing Profits

Consistent portion control is one of the most effective beverage cost reduction strategies available to bar owners, yet it's frequently overlooked or inconsistently applied. The difference between a 1.5-ounce pour and a 2-ounce pour might seem negligible on a single drink, but across hundreds of cocktails per week, that extra half-ounce represents significant profit loss. Implementing strict portion control measures ensures that every drink meets your cost targets while maintaining the consistency that keeps customers coming back.

Measured pourers and jiggers are the foundation of effective portion control. Free-pouring might look impressive, but even experienced bartenders can vary by 0.25 to 0.5 ounces per drink, especially during high-volume periods. Installing measured pourers on your liquor bottles guarantees that every shot is exactly the size you've designed your recipes around. For establishments that prefer the aesthetics of free-pouring, training bartenders to use jiggers consistently is essential. Regular pour tests, where managers check bartender accuracy with marked shot glasses, help maintain standards and identify team members who need additional training.

Recipe standardization goes hand-in-hand with portion control. Every cocktail on your menu should have a documented recipe with exact measurements for each ingredient. These standardized recipes become the foundation of your liquor inventory control system, allowing you to calculate theoretical usage and identify variances. When everyone follows the same recipe, you ensure consistent quality, accurate costing, and better inventory tracking. Many successful bars post laminated recipe cards at each station or use tablets with recipe apps to make it easy for bartenders to follow specifications exactly.

Portion control tools extend beyond pourers to include garnishes and mixers, which can also impact your bar profit margins. A heavy hand with expensive garnishes like fresh herbs or specialty bitters adds up quickly. Similarly, over-pouring mixers dilutes your cocktails and increases costs. By establishing clear standards for every element of your drinks and providing your team with the tools to execute consistently, you create a culture of precision that protects your margins while ensuring every guest receives the same high-quality experience.

Turning Food and Beverage Waste Into Creative Menu Opportunities

Progressive bar operators are discovering that effective liquor inventory control isn't just about preventing waste—it's also about creatively repurposing ingredients that might otherwise be discarded. This approach to beverage cost reduction transforms potential losses into profitable menu items while demonstrating environmental responsibility that resonates with modern consumers. By viewing surplus or aging inventory as an opportunity rather than a problem, you can create unique offerings that differentiate your bar from competitors.

Fruit and herb garnishes that are approaching the end of their freshness can be repurposed into house-made syrups, shrubs, and infusions that add complexity to your cocktail program. Citrus peels become oleo saccharum or dehydrated garnishes, while slightly wilted herbs can be muddled into specialty drinks or steeped into simple syrups. These value-added preparations not only reduce waste but also allow you to create signature ingredients that can't be easily replicated elsewhere, giving your bar a unique identity and justifying premium pricing.

Slow-moving spirits present another opportunity for creative menu development. Rather than watching premium bottles gather dust, feature them in limited-time cocktails or create a rotating "bartender's choice" program that highlights underutilized inventory. Many bars successfully use flight programs or tasting menus to introduce customers to slow-moving products, often discovering that certain items just need better promotion rather than being poor performers. This proactive approach to liquor inventory control prevents the write-offs that occur when bottles expire or become unsellable.

Consider implementing a zero-waste cocktail program that makes creative use of every ingredient. Juice pulp becomes ingredients in house-made sodas or is incorporated into food menu items. Coffee grounds from espresso martinis can be repurposed into coffee liqueur infusions. Even egg whites left over from yolk-forward dishes can be used in sours and fizzes. By systematically identifying waste streams and brainstorming creative applications, you engage your team in improving bar profit margins while building a reputation for innovation and sustainability that attracts environmentally conscious customers.

Training Your Team to Become Waste Reduction Champions

Even the most sophisticated bar inventory software and waste reduction systems will fail without buy-in from your team. The bartenders, barbacks, and servers who handle your inventory daily are your frontline defense against waste, and their habits directly impact your bar profit margins. Creating a culture where every team member understands the financial impact of waste and takes ownership of inventory control transforms your entire operation from reactive to proactive.

Start by making the business case transparent. Many bartenders don't realize that over-pouring a half-ounce on each drink in a busy Saturday night shift can cost the bar hundreds of dollars. Share the numbers with your team—show them how waste impacts profitability and, ultimately, their job security and tip potential. When staff understand that better liquor inventory control means a healthier business that can afford competitive wages and stay open long-term, they become invested in the outcome. Consider implementing incentive programs that reward teams for hitting variance targets or reducing beverage costs, creating positive motivation for careful inventory practices.

Comprehensive training programs should cover all aspects of beverage cost reduction, from proper pouring techniques and recipe adherence to inventory handling and storage procedures. Hands-on practice with jiggers and pourers helps bartenders develop muscle memory for accurate measurements. Role-playing scenarios where staff identify potential waste situations and discuss solutions builds problem-solving skills. Regular refresher training ensures that standards don't slip over time and gives you opportunities to introduce new techniques or address emerging issues. Documentation of all procedures creates a training resource for new hires and a reference for experienced staff.

Empowerment is the final piece of effective team training. Encourage staff to identify waste sources and suggest improvements—they often spot inefficiencies that management overlooks. Create a system where team members can easily report problems like leaking bottles, malfunctioning equipment, or recipe issues that lead to waste. Regular team meetings focused on inventory results foster accountability and allow for collaborative problem-solving. When bartenders feel like partners in the business rather than just employees, they naturally take more care with inventory and become genuine champions of waste reduction.

Tracking individual performance through your bar inventory software can also support training efforts. When you can show a bartender that their station has higher variance than others, it creates a concrete learning opportunity. Similarly, recognizing team members who consistently maintain tight inventory control reinforces positive behavior. By combining education, accountability, and recognition, you build a team culture where liquor inventory control becomes second nature, protecting your bar profit margins while elevating the professionalism of your entire operation.

Topics: Bar inventory, Hotel Inventory, wine inventory, managing liquor inventory cost, Liquor cost, Liquor Inventory savings, wine inventory app, wine inventory solution, wine inventory system, warehouse inventory

Loss Prevention: The Bar Manager's Key to Quick Profit Growth

Posted by Nick Kaoukis on Thu, Aug, 16, 2012 @ 13:08 PM

How Keeping Close Tabs On Your Liquor Supply Can Both Cut Costs & Generate Revenue

Inventory ControlIndustry studies have consistently shown that a full 25% to 30% of a bar's liquor inventory never converts into registered sales. That is the equivalent of about six to eight 1.25 oz portions per bottle (which should yield at least 25 portions.) This loss of liquor volume--due to unauthorized comps, over-pouring, spillage or theft--should be of great concern to any bar manager. 
While losing 25% of a $25 bottle may not seem like a very serious problem--an unavoidable cost of doing business--the true cost is much greater than that $6 or $7 per bottle. The question you need to ask yourself is: Where is this lost liquor going? And how is it affecting sales? For instance, if your bartender is not pouring 1.25 oz portions, but is instead pouring 2 oz portions (say, perhaps, to curry favor with clients and receive a bigger tip), you're not just losing liquor volume, you're also losing potential sales. Where the customer may have been disposed to buy three drinks (3.75 ounces), he may now be content to buy just two 2-ounce drinks. Your bartender's actions, in this case, haven't merely cost you a dollar's worth of liquor, they may well have cost you $6-$8 in lost sales revenue (depending on how you price your drinks). And that's just for one customer buying two drinks. How often is this occurring? What if your bartender also happens to be giving away free drinks without your knowledge or authorization? The point is: "shrinkage" does not only affect supply costs, it can also affect revenues in a big way. 

That's why loss prevention is so important. The profitability of your business depends on whole bunch of variables--the location of your establishment, the overall economy, ever-changing customer tastes.... Achieving profit growth can be difficult and can rarely be accomplished overnight. Increasing the price of your drinks is risky, and can prove more harmful than helpful as far as your bottom line is concerned. And growing your clientele usually takes time. The best way to increase profits in the short-term, therefore, is not to try to fiddle with pricing or to increase your client base. (Of course, this is something you should always be doing. But it is not easy to do in the short-term.) The quickest way to increase revenue is to make the most of the clients you're already serving. And one way to do this is to improve operations by getting tighter grip on your inventory. Loss of liquor supply at double-digit levels is not an "unavoidable cost of doing business". It is "bad business". And it is entirely avoidable. Put simply, loss prevention can pay big dividends. What's more, it can be achieved quite quickly through the implementation of a quality liquor inventory control system.

Topics: liquor inventory, Bar inventory, bar inventory levels, bar efficiency, bar profitability, Bar Management, Liquor cost, Liquor Inventory savings, alcohol cost, Increasing Profits, Reducing Liquor Costs, bar control, inventory control, managing liquor costs

Myths About Managing a Bar That Could Hurt Your Business

Posted by Nick Kaoukis on Thu, Aug, 02, 2012 @ 16:08 PM
By Douglas Robert Brown
Atlantic Publishing
 

Myth: Bartending School Is Vital for a Bartender

FalseMany of the best bartenders learn most of their useful trade while at work. This is because bartending schools vary widely in quality. Some emphasize the preparation of rarely requested drinks without stressing useful skills such as bar management, customer satisfaction, and customer safety. If you are hiring a bartender, you should consider the school he or she has attended, but testing practical skills will give the best clue of how many useful skills the person has for waiting on your bar. If you are considering attending a bartending school, investigate the school to make sure that you will be taught skills such as organization and techniques of serving. A good bartending school or course will emphasize dealing with customers. Be wary of a bartending school that is more of a "drink mix" school, stressing mixing many types of drinks without teaching anything besides drink preparation. There are many of these sorts of schools out there, which claim that a bartender's greatest asset is knowing how to mix an endless variety of drinks. Learning to mix the latest drink is relatively simple once one looks up the recipe, and most patrons will order the most popular drink of the moment rather than some obscure mix. A bartender with a good grasp of people and basic bartending techniques is usually more useful than the bartender who only knows how to mix hundreds of drinks from memory but has few skills besides. In some cases, an employee with a hospitality degree is better able to handle the bar job than someone who has attended a bartender school.
 

Myth: If You Hire Experienced Employees, There Is No Need to Train Them

 You still need to train your employees to ensure that they understand what you want them to do. In cases where an employee has worked at another establishment for a while, you may actually need to provide additional training to allow the employee to get used to the way you want things done versus how they did things at their previous job.


Myth: Hiring Younger Serving Staff Is Best

Many bar managers mistakenly believe that hiring young female servers will help ensure a high customer loyalty. This is based on the belief that middle-aged men are the main patrons of bars, which is no longer the case. When hiring servers or other staff, you should consider experience and skill over age or physical appearance. In most states, hiring based on age or appearance is discriminatory and can lead to lawsuits.


Myth: The Customer Is Always Right

Bar managers want the customer to be happy enough to return and satisfied enough to recommend the establishment to others. It is never wise to argue with a customer, and if the difference of opinion is something quite small, it is better to humor the customer in order to avoid making him or her feel embarrassed. On the other hand, if the customer insists that he or she is not intoxicated and can drink more, for example, then they should be refused further drinks.


Myth: Security Staff Is Vital in Today's Bar

Security does add a certain peace of mind, but at many establishments, it is still the bartender who acts primarily as the security force of the bar. Where your security comes from depends on your location and bar. If you decide you do not need a separate security staff, however, make sure that the bartender or some other personnel are willing to help customers in case of an incident.


Myth: To Run a Successful Bar, Just Serve Great Drinks

While quality drinks are a key to bar success, many people go to bars to spend time with others. If you serve good drinks but offer exceptional atmosphere and service, you are likely to do well. In today's competitive world, great drinks alone are not enough. Bar managers need to have good financial planning and careful advertising and marketing and offer great customer service in order to be a success.


Myth: You Can Cut Corners to Increase Profits

Reducing costs or cutting corners (reducing the size of drinks or firing staff) is unlikely to help. Customers expect more from bars than ever before. Offering them less is unlikely to bring you the results you want. If you are just starting out, it may take months to see a profit. If you have been in business for a while, increasing customers and getting more from each customer by encouraging spending and lingering are far better strategies than downsizing in order to make a profit.


Myth: You Must Keep Expanding in Order to Make a Profit

Many bar managers think that in order to make a large profit, they need to dabble in everything. For this reason, many bars spend large amounts of money setting up dance floors, live acts, larger establishments, and restaurants. When you are just starting out, though, it is often best to keep things simple. Do not expand randomly, assuming that spending more money will bring in more money. Only expand after careful research and weighing the potential risks and benefits. You do not want to get into debt for a venture that is unlikely to work for your bar.


This article is an excerpt from the The Professional Bar & Beverage Managers Handbook: How to Open and Operate a Financially Successful Bar, Tavern and Nightclub, authored by Douglas Robert Brown, published by Atlantic Publishing Group. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:

Atlantic Publishing Company
Amazon.com

Topics: Bar staff, bar profitability, NightClub Management, bartenders you can trust, bar business, Bar drinks, Liquor cost, Bar products, drink recipe, liquor products

Making the Most of Your Liquor: Extracting an Extra Ounce of Profit

Posted by Nick Kaoukis on Mon, Jul, 18, 2011 @ 11:07 AM
By Chris Parry
Atlantic Publishing
 

Upsizing is EssentialSaving on every ounce of alcohol

When you go to the movies, quite often you can buy a double-sized popcorn for only $0.75 more than the $3.50 regular size. This would seem to be an astonishing bonus for the customer, so why does the cinema operator push this "up-sizing" so hard? Quite simply, because they're selling about $0.04 worth of popcorn for that extra $0.75. That second portion might not bring as large a profit margin as the first, but it's still profit. Your drinks run the same way - if you can get another buck out of a customer selling a drink that costs you $0.45 to prepare, it's worth doing.

  • Consider the cost per ounce of your well spirits. Let's assume you're using El Cheapo brand tequila at a base cost of $7.54 a liter. That would mean that an ounce of that spirit is costing your establishment $0.22, while a more-expensive brand of tequila, let's say Cuervo for the sake of this example, might come at a base cost of $14 per liter, or $0.41 per shot. Common thinking might lead you to say that by using the cheaper tequila you're saving yourself $0.19 on every drink sold. But, if you consider the alternative of up-selling the more expensive spirit for an extra $0.80 or so, you're actually making an extra $0.61 profit on every up-sized drink.

  • Offer your customers a discount to spend more than they planned. This works in other areas, too. Turning a single into a double for an additional dollar, or selling half-price burgers with every shot of a specific brand of spirit, brings you more money per order, while bringing your customers added value. Your profit margin might not be as high, but you'll be extracting more money from your customers than they might otherwise have spent - a definite win-win.

  • Up-selling. Most bar customers will bring out more money than they initially want to spend -just in case - especially those that don't have easy access to it through ATM machines and credit cards, so it's imperative that your staff don't let those customers walk out the door having spent less than they planned. Incentives for up-selling are commonplace in the theater and fast-food industries, so why not offer your staff an incentive to up-sell and watch your better staff earn a few extra dollars while earning you hundreds?

  • Incentives. For example, if a member of your staff engages someone in conversation and discovers they're looking for somewhere to hold a private function, birthday party, girls' night out - any large gathering of people - there's certainly no harm in making it worth their while to bring that prospective client to you. Twenty dollars here, $50 there - even a percentage of the bar take - if you offer the incentives, you'll be surprised how far people will go to bring you new business.


This article is an excerpt from the Food Service Professional Guide to Bar & Beverage Operation, authored by Chris Parry, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:

Atlantic Publishing Company 
Amazon.com

Topics: NightClub Management, bar business, Bar drinks, Bar Management, Liquor cost, alcohol cost

Pricing Your Drinks: The Need for a Structured Approach

Posted by Nick Kaoukis on Wed, Jul, 13, 2011 @ 11:07 AM
pricing drinksBy Chris Parry
Atlantic Publishing
 

Structuring a Price List


Guesswork just won't do in today's corporate world. Figuring that if your scotch costs you $14 a bottle you can sell a shot for $3, is just a little hit-and-miss when you take in all the other potential costs, like rent, insurance and wages, that your establishment has to cover over the course of a month. It's possible you might be able to charge less than $3, but it's also possible you should be charging way more. Take these factors into account when making your next price list adjustment:

  • Market positioning. Take a look around at what your competitors are charging. Figure out if you need to undercut them or match their level. Does your establishment give added value enough to increase your prices and still draw a good crowd? Are you a level above them in terms of services and product? Are you evenly matched? Are you looking for a more "low rent" crowd? Price accordingly.
  • The competition. They're not always right, but if they've been around a while, your direct competitors probably have a good gauge of what your local customers are prepared to pay for a drink. Take the time to look around and take particular note of any specials they offer on certain nights.
  • Customer demographics. Are your patrons blue-collar workers? Are they white-collar? Do they have families to get home to or are they likely to stay all night and spend every penny? Are they young adults or senior citizens? These all impact what you can charge without losing clientele, and you should have the information already from your market research.
  • Embrace simplicity. It's far better for your customers and staff to have to deal with a simple pricing structure as opposed to forcing them to break their brains over an intricate maze of differently priced products. Set across- the-board levels of prices; for example, well spirits might cost $3, middle-shelf $3.50 and top-shelf $4. Of course there's always going to be the occasional variation, but for the most part, a three-tiered system gives you flexibility in pricing without your staff continually needing to check a price list or hand out handfuls of change.
  • Include tax in your pricing. There's nothing worse than getting $0.84 change from a five- dollar bill on every drink you buy and getting home with a pocket full of silver and copper. If you're going to set your prices at a round level, include the tax in that price so you can use price levels to your advantage. If your alcohol tax rate is 10 percent, the non-tax price for a shot that costs your patrons $3.50 would be $3.18 ($3.18 plus tax of $0.32 equals $3.49). Let your accountant do the math, not your bar staff. Sales tax is a complicated matter that varies dramatically from state to state. Prior to estab­lishing the net price inclusive of tax, discuss the issue with your accountant and state Department of Revenue. Don't find out later in a five-year audit that you've been calculating the tax incorrectly.


This article is an excerpt from the Food Service Professional Guide to Bar & Beverage Operation, authored by Chris Parry, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:

Atlantic Publishing Company 
Amazon.com

Topics: bar business, Bar drinks, Bar Management, Liquor cost, alcohol cost, drink recipe