Expert Advice on Hospitality Topics

How to Calculate Liquor Cost in 5 Simple Steps (2026)

Posted by Nick Kaoukis on Tue, Oct, 06, 2026 @ 15:10 PM
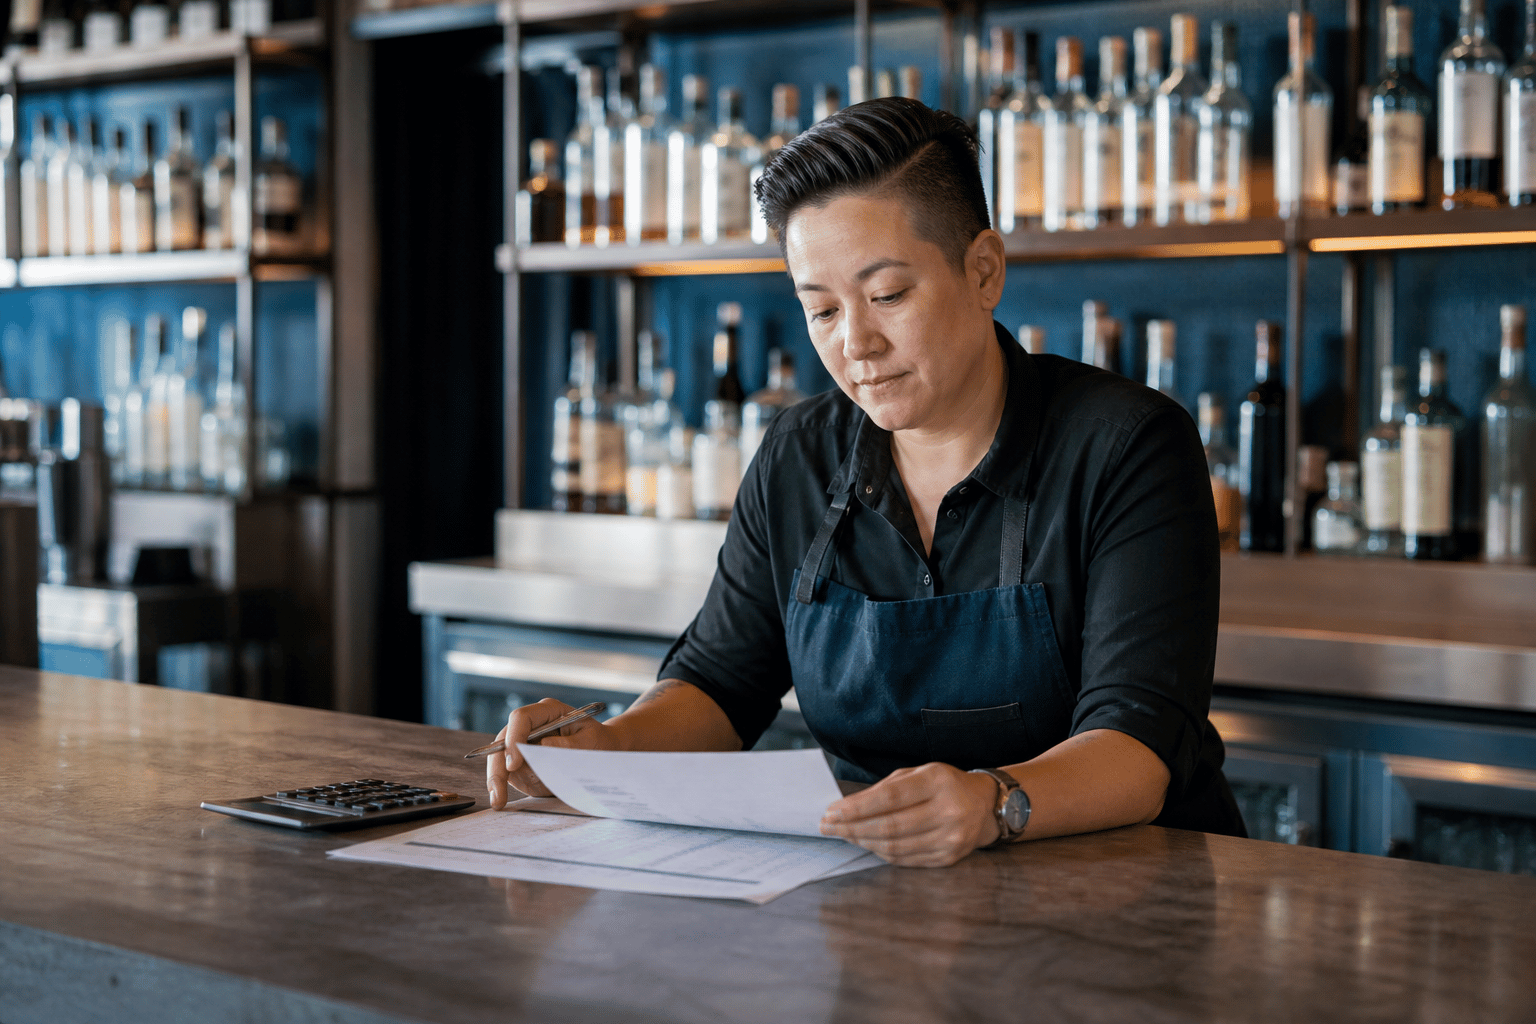
Hospitality manager reviewing an inventory worksheet and calculator at a bar counter
Illustrative AI-generated image of a liquor inventory review.

Liquor cost percentage equals the cost of liquor consumed divided by liquor sales for the same period, multiplied by 100. Your purchases alone do not tell you what you consumed. Stock remaining on the shelf belongs in the calculation.

For an illustrative bar with $600,000 in annual liquor sales, a four-percentage-point gap between actual cost and its own target represents $24,000 in additional product cost. That gap deserves investigation, not an automatic accusation of theft.

Scannabar supports liquor inventory control with bottle-level counting and usage reporting. The five steps below explain the calculation behind those numbers.

For the complete inventory process behind this calculation, see our liquor inventory and cost-control guide.

Quick Guide: Calculate Liquor Cost in Five Steps

  1. 1. Match Reporting Dates and Categories: Align inventory boundaries with sales dates and your beverage categories.
  2. 2. Value Beginning Inventory: Record full and partial bottles using a consistent cost basis.
  3. 3. Record Purchases, Returns, and Transfers: Reconcile deliveries and movements within the reporting period you selected.
  4. 4. Calculate Usage Cost: Deduct ending stock after adjusting opening inventory for recorded movements.
  5. 5. Divide Usage Cost by Liquor Sales: Convert consumption cost into a percentage of matching sales revenue.

Calculate Your Bar's Liquor Cost Percentage

1. Match Reporting Dates and Categories

Choose a period with inventory counts at its opening and closing boundaries. Pull POS sales for those same dates and locations. A count taken after additional service cannot reliably close an earlier sales period unless you account for intervening activity.

Separate spirits from wine and beer when you need category-level answers. Compare the same ingredient scope on both sides: spirits-only costs should not be divided by all restaurant revenue. Consistent scope makes beverage variance easier to interpret.

2. Value Beginning Inventory

Beginning inventory is the cost value of stock on hand at the start of the period. Include the back bar, service stations, storage, and any other locations inside your reporting scope.

Record bottle size, quantity, and partial contents consistently. Use a documented valuation policy agreed with your accountant rather than switching cost methods between counts. Review your counting method when partial-bottle measurements vary between staff.

3. Record Purchases, Returns, and Transfers

Include liquor received during the period, reconcile invoices to deliveries, and deduct documented supplier returns or credits once. An invoice entered twice inflates consumption even if every bottle was poured correctly.

For outlet reporting, add transfers in and deduct transfers out at cost. Transfers within a whole-property scope cancel out; do not treat them as new purchases. Keep wine stock and other categories separate if your calculation covers liquor only.

4. Calculate Usage Cost

Usage cost equals beginning inventory plus net purchases plus transfers in, minus transfers out and ending inventory. All inputs are dollar values at cost, not selling prices.

Usage cost = Beginning inventory + Net purchases + Transfers in − Transfers out − Ending inventory.

Count ending inventory using the same scope and valuation policy. Usage includes sold product, documented waste, complimentary drinks, and unexplained depletion. It is a measure of consumption, not proof of its cause. Inventory reports help organize the review.

5. Divide Usage Cost by Liquor Sales

Divide usage cost by net liquor sales for the matching period and multiply by 100. Exclude tips and taxes from sales consistently with your accounting policy. If sales are zero, the percentage is undefined.

Liquor cost percentage = Usage cost ÷ Net liquor sales × 100.

Compare your result with your recipe-based target and prior periods. Supplier costs, discounts, sales mix, measurement errors, and over-pouring can all change the result.

Worked Example: A Weekly Liquor Cost Calculation

This hypothetical example assumes no transfers. Opening stock is $8,400, deliveries total $5,200, returns are $180, and ending stock is $9,060. Usage cost is $8,400 + $5,200 − $180 − $9,060 = $4,360.

Illustrative liquor cost calculation
MeasureResult
Usage cost$4,360
Net liquor sales$18,200
Liquor cost percentage23.96%
Gross profit before other expenses$13,840

If the recipe-based target were 20%, expected cost would be $3,640. The $720 difference needs reconciliation against records, prices, waste, and portions. It is not automatically recoverable profit.

Why Can Purchases Differ From Liquor Consumed?

Purchases increase stock; consumption reduces it. A large delivery near period-end can increase purchases without increasing usage by the same amount. Ending inventory removes the unconsumed stock from the calculation.

Keep beer and dry goods in their appropriate categories so receiving activity does not distort a spirits-only calculation.

How Does Liquor Cost Affect Gross Profit?

Lower product cost increases gross profit at unchanged sales, but net profit also depends on labor, occupancy, and other operating expenses. A strong liquor margin does not establish that the entire business is profitable.

Cheryl Stanley, Senior Lecturer at Cornell's Nolan School of Hotel Administration, covers pricing and controls in her beverage program course. Those decisions should be assessed together, rather than treating one cost ratio as the whole business.

How Scannabar Supports Liquor Cost Control

Scannabar provides liquor inventory software with bottle-level measurement, usage reports, and POS reconciliation. Consistent inventory inputs support both the cost calculation and the investigation that follows it.

Use Scannabar's inventory controls to build a culture of accountability that protects staff from false accusations. Review the reporting workflow with your team before making operational changes.

FAQs About Liquor Cost Calculations

Is liquor cost the same as pour cost?

The terms often describe the same period cost ratio. A per-drink recipe cost is different: it describes expected ingredient cost for one serving. Scannabar's usage reports support the inventory-based view, which includes depletion that recipes and recorded sales alone do not explain.

How often should you calculate liquor cost?

A weekly review is a practical starting point for an active bar, provided counts and sales share the same boundaries. Scannabar's counting workflow supports frequent reviews. Choose a cadence your team can execute consistently and add spot checks for high-value stock when appropriate.

Does a high liquor cost prove theft?

No. High cost can reflect pricing, sales mix, supplier changes, recording errors, waste, or unauthorized usage. Scannabar's product-level reports help narrow the review, but records and operational evidence are still necessary before attributing a discrepancy to an individual.
Topics: managing liquor inventory cost, Liquor cost, Reducing Costs, Reducing Liquor Costs, controling costs, managing liquor costs

Insider Theft Can Have a Major Effect on Bar Profits

Posted by Nick Kaoukis on Tue, Sep, 27, 2011 @ 15:09 PM
By Elizabeth Godsmark
Atlantic Publishing
 

bartender theftThis is an alarming fact: most types of beverage operations lose a crippling percentage of profits through insider theft. The vast majority of employees in the beverage industry are honest and hardworking; it is the small minority of staff that can ruin your business through dishonesty. Insider theft can often escalate if there are weaknesses in the following general areas of the operation:

  • Lack of supervision. Theft from behind the bar, storeroom or storage areas is a major problem. Curb losses by increasing supervision, either in person or by means of strategically positioned security cameras.
  • Proprietor attitude. Don't make matters worse by treating all employees with suspicion. Get the honest staff on your side.
  • Weak management. Unfortunately, some beverage managers compound the issue of insider theft by turning a "blind eye" and simply increasing prices to cover "shrinkage." Owners need to question unwarranted price rises.
  • Pouring costs A common danger area. These costs need to be carefully monitored, especially in relation to bartender productivity.
  • Inventory records. This is one of the easiest areas for dishonest employees to "fiddle the books." Tighten up your record keeping. Never leave inventory control to one person. Double-check.
  • End-of-shift cash count. Another prime target area for insider theft. Never let a bartender reconcile the cash in the register at the end of his or her shift.


Bartender Theft: Top Ten Ploys

Controlling theft behind the majority of bars is no mean task; eliminating it altogether is virtually impossible. Temptation is a fine thing, and unfortunate­ly, the opportunity for bartender theft is overwhelming. However, in the interests of long-term survival, you have no choice but to tackle the problem head on. Be wary of the following top-ten common ploys:

  • Open theft. A bartender pours a drink, doesn't ring the cash register and puts the cash in a "holding" place, such as the tip jar.
  • Overcharging. Bartender pockets the difference. A variation is to charge regular prices but ring up "Happy Hour" prices and, again, pocket the difference.
  • Ringing "00" on the cash register. The bartender simply steals the value of the drink.
  • Overpouring. Bartender hopes to get a heavy tip.
  • Underpouring. Bartender keeps a mental note of the number of half measures poured throughout the evening and then thieves the equivalent value in drinks, gives them away or drinks them him-or herself.
  • Rounds of drinks. Bartender rings up for a "round" rather than separate items. It makes it easier to inflate the overall price of a round of drinks, particularly if guests are unfamiliar with individual prices.
  • Shortchanging. Common variations include: counting aloud while handing the customer less money, distracting the customer by sliding the change along the bar, and giving change for lower -denomination bills (while keeping the difference).
  • "Soft" inventory. Bartender neglects to charge for the mixer component of a drink.
  • Substitution - bringing in own liquor. This is often done with vodka because it is odorless and looks like water. Dilution is another similar ploy.
  • Padding the tab. The bartender pencils in an inflated total and later erases it, replacing it with the correct total. Warning! Ban pencils from behind the bar.


Less Common (But Equally Damaging) Employee Theft

The more experienced the dishonest employee, the better equipped he or she is to manipulate the system. Thieving members of staff are quick to detect exactly how much an owner really understands about the business. In the beverage industry, take nothing for granted. Alert yourself to the following, somewhat extreme, possibilities.

  • Reusing closed tabs. The bartender appears to ring up the drink price but, in actual fact, only halfway enters the tab into the register. He or she then hits "0" to give the impression of ringing it in.
  • Over-ringing. When the customer isn't looking, the thief over-rings an amount on the tab and then re-rings the tab for less than the amount charged.
  • "Paid outs." The bartender claims that the money was refunded for various reasons, such as faulty cigarette machines.
  • Jigger substitution. The bartender brings in his own shot glass that looks identical to the official jigger but is actually smaller. Several short measures over a shift add up
  • Changing shifts. It is easy for the thief to make, serve and collect several drinks during a busy "hand-over" period.
  • Deliberate mistakes. Drinks are then returned and resold or given to a friend.
  • Breaking empty bottles and pretending they were full. Full bottles are then requisitioned to replace the "broken" empty bottles.
  • Substituting water in the drip tray. The bartender pretends he or she had to waste a pint to clear the lines and then pockets the difference.


    This article is an excerpt from the Food Service Professional Guide to Controlling Liquor Wine & Beverage Costs, authored by Elizabeth Godsmark, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:

    Atlantic Publishing Company
    Amazon.com

Topics: bar inventory levels, bar business, Bar Management, Reducing Costs, bar control, Control

The Bottom Line: Reducing Costs & Increasing Profits, Part 1 of 2: The Profits

Posted by Nick Kaoukis on Wed, Jul, 06, 2011 @ 09:07 AM
Cutting liquor costsBy Chris Parry
Atlantic Publishing
 

Part 1 of 2: The Profits

 
What does each drink cost you?
Without profits, you're out of business, but so many managers see profits as what the owners worry about. Your job is as much to grow profits as to sustain them, so consider putting a little elbow grease into the growth of your establishment by learning about the nickel and dime stuff. A good bar operator needs to wear a number of hats, but the four most important are that of promoter, psychologist, host and accountant. This isn't to say that you need to be of professional standard in all four areas, but you do need a working knowledge of each area, so that you can fine-tune those aspects of your business. On the accounting side of things, you need to be able to assess what every piece of your business costs. Also, as your spirits and liqueurs are a very large segment of your inventory, you should learn exactly how much each and every drink you sell actually costs you. Follow these exercises and you'll be able to assess exactly which drinks bring you the highest profit margin and which drinks could use a price increase.
  • Cost per ounce. There is 33.8 ounces in a liter, so if you're paying $15 a liter for a certain spirit, simply dividing that amount by 33.8 will bring you the beverage's ounce cost (in this case, $0.44). If your bottle size is 750ml, then divide the bottle cost by 25.35 to get the ounce cost. Likewise, dividing a 500ml bottle by 16.9 will give you that product's ounce cost.
  • Total beverage cost. When calculating what it costs you to provide a mixed drink to a customer, simply figure out the ounce cost of each item in the drink. A half-shot means adding half the ounce cost of that shot, whereas a double shot would mean doubling the ounce cost. Make sure to include every aspect of the drink, such as mixers, dashes of cordial and garnishes. The total of each of these ounce costs will be your "beverage cost" for that drink.
  • Cost percentage.  When you're investing in inventory, you want to know that you're getting a good return on your money and the best way to figure out your percentage return is to estimate your cost percentage for each drink you sell. Simply divide your ounce cost (or bottle cost) by the sale price you've set for that item and then multiply that number by 100. The total will tell you exactly what percentage of the final drink price you are spending on the purchase of its raw contents. The lower the number, the more profit you're making.
  • Gross profit margin. To figure out each item's gross profit, simply deduct the cost price from the sale price. To figure out your gross profit margin, take the gross profit, divide it by the sales price and multiply it by 100. The figure remaining is your gross profit margin. You may well find it varies greatly from beverage to beverage. This will tell you which items have a high enough profit margin to push on your customers and which items are just making up the numbers.


This article is an excerpt from the Food Service Professional Guide to Bar & Beverage Operation, authored by Chris Parry, published by Atlantic Publishing Company. This excerpt has been reprinted with permission of the publisher. To purchase this book go to:

Atlantic Publishing Company 
Amazon.com

Topics: bar business, alcohol cost, Increasing Profits, Reducing Costs, Reducing Liquor Costs, inventory control