A cocktail tasting event can produce strong revenue in a single evening, but only if the ticket price covers what the night actually costs. Many operators price the pour and forget the person pouring it, the prep labor behind the batches, and the contingency that protects margin when the unexpected happens.
This guide walks you through a bottom-up costing method for a cocktail tasting event: portions and ingredient costs, staffing and other operating expenses, ticket pricing and break-even calculation, opening stock and transfers, contingency planning, and a post-event profitability review. Every financial figure in this guide is hypothetical and illustrative. Use your own supplier invoices, labor rates, and venue costs before setting a ticket price.
Key Takeaways: Costing a Cocktail Tasting Event
- Cost every line item before setting a ticket price: ingredients, staffing, supplies, venue expenses, and a contingency buffer.
- Calculate your break-even guest count so you know the minimum ticket sales needed to cover fixed costs.
- Set up opening stock transfers from your main inventory and document every bottle that moves to the event space.
- Scannabar supports the inventory tracking that lets you reconcile event stock against actual consumption after the evening ends.
- Review actual profitability against your projections to improve costing accuracy for the next event.
Why Bottom-Up Costing Protects Your Margin
The fastest way to underprice a tasting event is to start with a pour cost target and work backward. An 18% pour cost tells you what the spirit costs per ounce. It says nothing about the four hours of prep labor, the extra glassware rental, the printed tasting cards, or the two staff members you need behind the bar.
Bottom-up costing works the other direction. Add up everything the event actually costs, divide by a realistic guest count, and only then check the result against industry pour cost ranges as a sanity check. FSM.How's guide to beverage control notes that average pour costs for hotel and bar operations typically range from 18% to 24%, which provides a useful reference point for tasting-event pricing. The pour cost becomes a verification step, not a starting point.
For a bar generating $500,000 in annual revenue, a single under-priced event that loses $2,000 is a rounding error on the P&L. Run four under-priced events per quarter and you have an $8,000 annual drag on margins that could have been prevented by spending one hour on the math before printing the first ticket.
How to Calculate Portion and Ingredient Costs
Start with the drinks themselves. Define the format: how many cocktails per guest, what size each pour will be, and what ingredients each recipe requires.
Define Portions Per Guest
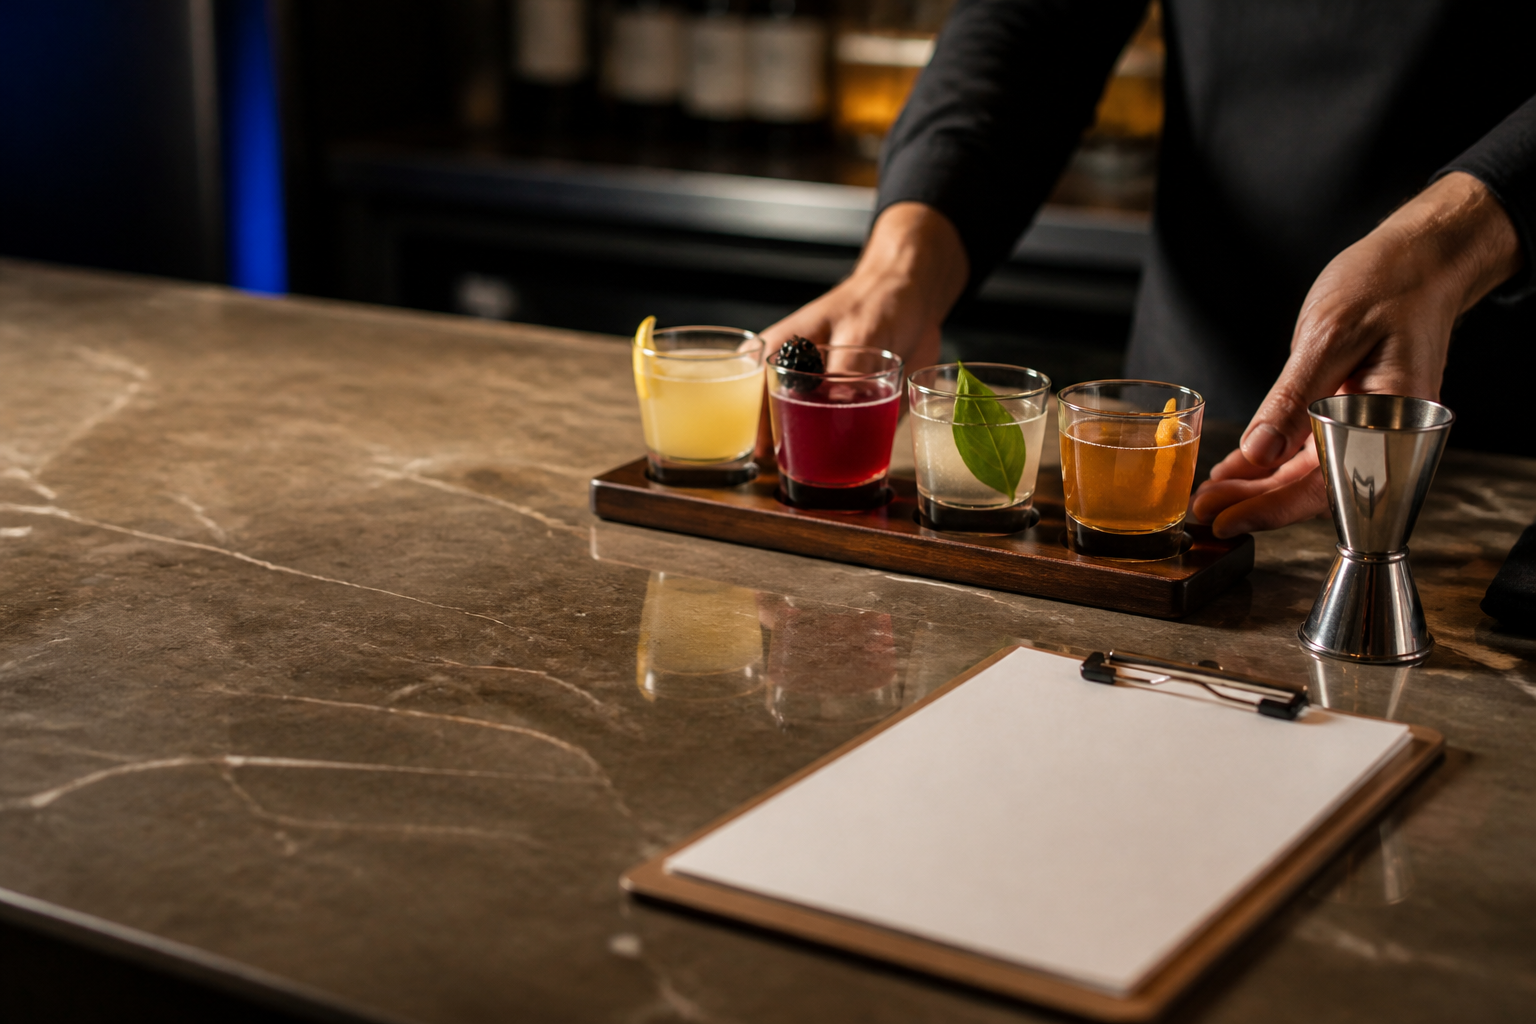
A standard tasting format serves three to five cocktails per guest, with portions smaller than a full menu cocktail. A two-ounce tasting pour is common. If you are serving four cocktails at two ounces each, every guest consumes eight ounces of finished cocktail, which translates to a specific volume of each ingredient based on your recipes.
Multiply per-guest consumption by your expected guest count. For a 40-person event serving four cocktails each, you are producing 160 individual drinks. That volume drives every purchasing and preparation decision.
Cost Each Recipe at Tasting Portions
Use your actual supplier invoices to cost each tasting cocktail at its reduced portion size. A recipe that costs $2.80 per full-size serving may cost $1.50 per tasting pour, depending on the ingredients and their proportional scaling.
Include every component: base spirit, modifiers, syrups, citrus, garnishes, and ice. Do not estimate garnish cost as zero because "you already have limes." Those limes have a cost, and at tasting-event volume, garnish consumption is concentrated into one evening rather than spread across a week of service.
The following hypothetical table illustrates a four-cocktail tasting menu costed at tasting portions:
| Cocktail | Tasting Portion | Ingredient Cost per Serve |
|---|---|---|
| Citrus Gin Fizz | 2 oz finished | $1.40 |
| Bourbon Smoked Sour | 2 oz finished | $1.85 |
| Mezcal Paloma | 2 oz finished | $1.60 |
| Rum Old Fashioned | 2 oz finished | $1.55 |
Total ingredient cost per guest: $6.40. For 40 guests: $256.00 in total ingredient cost. These figures are hypothetical. Your actual ingredient costs will vary based on your recipes and supplier pricing.
How to Calculate Staffing and Other Operating Costs
Ingredients are rarely the largest cost of a tasting event. Staffing, supplies, and operational overhead often exceed the ingredient bill, especially when the event requires preparation the day before.
Staffing Costs
Break staffing into three phases: preparation, service, and breakdown. Your bartender may spend four hours batching syrups, juicing citrus, and prepping garnishes the day before, then five hours on the event night itself (setup, service, and cleanup). That is nine hours of labor per bartender.
If you need two bartenders for service and one barback, calculate their combined hourly cost including any applicable taxes and benefits. For a hypothetical $22 per hour average, two bartenders for nine hours each ($396) and one barback for six hours ($132) produces a staffing total of $528.
Supplies and Venue Costs
List every non-ingredient expense the event requires. Common line items include:
- Glassware rental or disposable tasting cups
- Printed tasting cards or menus
- Ice (purchased or produced, at actual cost)
- Napkins, straws, and bar consumables
- Any venue-specific charges (room rental, A/V, additional insurance)
For a hypothetical 40-person event, these costs might total $180. Larger events in rented spaces can run significantly higher. Get actual quotes before your costing is complete.
Total Operating Costs
Combine your ingredient, staffing, and supplies totals:
| Cost Category | Amount |
|---|---|
| Ingredients (40 guests x $6.40) | $256.00 |
| Staffing (2 bartenders + 1 barback) | $528.00 |
| Supplies and venue | $180.00 |
| Subtotal before contingency | $964.00 |
How to Set Ticket Pricing and Calculate Break-Even
With your total cost established, ticket pricing becomes an arithmetic exercise rather than a guessing game. The question is how many guests you need at what price to cover your costs and deliver your target profit.
Add a Contingency Buffer
Build a 10% to 15% contingency into your cost estimate. Unexpected costs surface in every event: a bottle that breaks during setup, a garnish order that runs short, a last-minute staffing addition. A contingency buffer absorbs these surprises without pushing the event into a loss.
For our hypothetical event, a 15% contingency on the $964 subtotal adds $144.60, bringing the total estimated cost to $1,108.60.
A Clearly Labeled Illustrative Break-Even Calculation
This example uses the hypothetical figures above. These are not recommended prices, supplier costs, or guaranteed outcomes.
Total estimated cost: $1,108.60. Target profit: $800 (an operator-defined goal for the evening). Required gross revenue: $1,908.60.
At 40 guests: $1,908.60 divided by 40 = $47.72 per ticket. Round to a clean price point: $50 per ticket.
At $50 per ticket with 40 guests, gross revenue is $2,000. After estimated costs of $1,108.60, the projected profit is $891.40.
Break-even guest count at $50 per ticket: $1,108.60 divided by $50 = 22.17, meaning you need at least 23 paid guests to cover costs. Every guest beyond 23 contributes approximately $43.60 in profit (ticket price minus per-guest ingredient cost of $6.40).
Check the Pour Cost as a Sanity Step
Ingredient cost per guest ($6.40) divided by ticket price ($50) equals a 12.8% pour cost. For a tasting event with premium spirits and labor-intensive preparation, this is within a reasonable range. If your pour cost calculates above 25% for a tasting format, revisit either your ingredient costs or your ticket price.
The pour cost check confirms your pricing is in a sensible range. It does not replace the bottom-up costing that established the ticket price. Those are two different functions.
How to Manage Opening Stock and Transfers
Tasting events pull stock from your main bar inventory. If those transfers are not documented, the main bar's variance report will show unexplained consumption, and the event's actual cost will be impossible to calculate.
Create a Pre-Event Pull Sheet
Before the event, prepare a transfer document listing every product that will move from your main inventory to the event space. Include product name, bottle size, quantity transferred, unit cost, and the name of the person authorizing the transfer.
This pull sheet serves two purposes. First, it tells your event team exactly what they will have to work with. Second, it creates the documentation your inventory system needs to reconcile the main bar's stock after the bottles leave the building or the storeroom.
Document Transfers on Both Sides
The sending location (main bar or storeroom) records a transfer out. The receiving location (event space) records a transfer in. Both sides of the movement must be captured so that neither location shows a phantom surplus or shortage.
For hotel operators managing events across multiple outlets, this is especially critical. A banquet prep area that borrows six bottles of vodka from the lobby bar storeroom can create a $120 discrepancy in the lobby bar's variance report if the movement is not recorded. That discrepancy wastes investigation time and potentially triggers an unfair review of lobby bar staff.
Plan for Contingency Stock
Pull slightly more product than your recipe calculations require. If your recipes call for three bottles of gin for 40 guests, transfer four. The fourth bottle is your safety margin against over-pouring, an extra guest or two, or a batch that does not turn out correctly.
Document the contingency stock on the same pull sheet. After the event, count what remains and record the return transfer. The difference between what you sent and what came back, minus documented waste, is your actual event consumption.
How to Handle Leftovers and Calculate Actual Profitability
The event ends. Guests leave. What remains on the event bar, in the batching station, and in the prep area tells you whether your costing was accurate.
Count and Return Unused Stock
Immediately after breakdown, count every unopened bottle and measure every open bottle that can return to the main inventory. Record the return transfer with the same detail as the original pull: product, quantity, condition, and the person handling the return.
Opened bottles that are not suitable for return to the main bar (due to quality, cross-contamination, or house policy) should be logged as event waste. Their cost belongs in the actual event cost, not in the main bar's unexplained variance.
Calculate Actual Consumption
Actual consumption = Opening transfer minus return transfer minus documented event waste. Convert that consumption into a dollar cost using the same unit costs from your original costing.
For our hypothetical event, if the opening transfer was $380 worth of spirits, $48 returned unused, and $15 was documented as event waste, actual ingredient consumption is $380 minus $48 minus $15 = $317. The planned ingredient budget was $256. The $61 overage reflects over-pouring, additional guests, or batch adjustments during the event.
Compare Projected and Actual Profitability
Lay the projected figures next to the actual results:
| Category | Projected | Actual | Variance |
|---|---|---|---|
| Ticket revenue (42 guests at $50) | $2,000 | $2,100 | +$100 |
| Ingredient cost | $256 | $317 | +$61 |
| Staffing | $528 | $550 | +$22 |
| Supplies and venue | $180 | $175 | -$5 |
| Total cost | $964 | $1,042 | +$78 |
| Net profit | $891 | $1,058 | +$167 |
This hypothetical event produced $167 more profit than projected, primarily because two additional guests purchased tickets. The ingredient overage and slight staffing increase were absorbed by the extra revenue and the unused contingency budget.
Document Lessons for the Next Event
Record what went right and what went wrong in a brief post-event review. Were portions consistent? Did you run short on any ingredient? Was staffing adequate for the guest count? Did the contingency buffer cover the unexpected costs?
These notes become the costing foundation for your next event. Each tasting you run should produce a tighter cost estimate than the last, reducing the contingency buffer you need and increasing the confidence behind your ticket price.
How Scannabar Supports Event Inventory Management
Tasting events create concentrated stock movements: a burst of transfers, a night of consumption, and a return of unused product. Without precise tracking, the event's actual cost blurs into your regular bar operations.
Scannabar's liquor inventory system tracks every bottle from receiving through transfer, consumption, and return. For event management, that means you can measure exactly what left the storeroom, what was consumed during the event, and what came back. Your event cost is calculated from verified stock data, not estimates.
For hotel operators running banquet tastings or private dining events, Scannabar's multi-outlet tracking keeps event inventory separate from daily bar operations. The banquet's variance does not contaminate the lobby bar's variance, and both outlet managers can review their own results independently.
In Conclusion: Price the Event From Cost, Not From Hope
A profitable cocktail tasting event starts with a costing sheet, not a ticket price. Calculate every ingredient, labor hour, and supply cost before you set the price. Build a contingency buffer that protects your margin against the inevitable surprises. Then sell tickets at a price that covers the full cost and delivers a profit you can justify.
After the event, close the loop. Count what remains. Calculate actual consumption. Compare projected and actual results. Use the difference to improve your next event's accuracy. Each tasting should be more profitable than the last because each costing gets tighter.
The alternative is pricing by instinct, hoping enough guests show up to cover costs you never calculated. For a bar that runs multiple events per year, that hope accumulates into thousands of dollars in preventable losses. Do the math once, and let the numbers run every event that follows.
FAQs About Costing a Cocktail Tasting Event
How many cocktails should a tasting event include per guest?
Three to five cocktails at tasting portions (1.5 to 2.5 ounces finished) is a standard range. Fewer than three feels sparse. More than five creates diminishing returns in guest experience and increases your ingredient cost. Match the number to your event duration and the complexity of your menu. A 90-minute event supports four cocktails comfortably.
Should you include food costs in the ticket price?
If you are serving food pairings, those costs belong in your bottom-up costing alongside ingredients and staffing. Cost each food item per guest, add it to the subtotal, and factor it into your ticket price. Do not treat food as a "bonus" that comes out of the kitchen's budget. Every expense that the event generates should appear in the event's cost sheet.
How do you handle no-shows and last-minute cancellations?
Your break-even calculation provides the cushion. If your event breaks even at 23 guests and you sell 40 tickets, five no-shows still leave you at 35 guests and a comfortable profit. Consider requiring prepayment to reduce no-show risk. If you offer refunds, set a cutoff date that aligns with when you place ingredient orders.
Can Scannabar help track event-specific inventory separately?
Scannabar tracks inventory by outlet and location, so event stock can be managed independently from daily bar operations. Transfer documentation and post-event return counts keep event consumption isolated. That separation means your event cost is calculated from verified figures, and your regular bar variance is not distorted by the event.
What is a reasonable contingency percentage for a tasting event?
Build a 10% to 15% contingency into your total cost estimate. First-time events should lean toward 15% because you have less data to predict unexpected costs. As you run more events and refine your costing, the contingency can decrease because your estimates become more accurate.
How do you determine actual profitability after the event?
Subtract all actual costs (ingredients consumed, staffing hours, supplies, and documented waste) from actual ticket revenue and any additional revenue such as drink upgrades or merchandise sales. Compare this figure to your projected profit. The variance between projected and actual is the data that makes your next event's costing more precise.